Categories
Blog

Profits, Options, Phantoms and Other Equity-Based Awards


Profits, Options, Phantoms and Other Equity-Based Awards

Summer 2022

Charles C. Shulman, Esq.
cshulman@ebeclaw.com
201.357.0577

Full article Profits, Options, Phantoms and Other Equity-Based Awards, published in Journal of Deferred Compensation  (WK Summer 2022)  See copy at: https://drive.google.com/file/d/19eBhlDz7nz0BCBKSy57Uh3lTmbhl-6zM/

Equity-based compensation allows employers to reward management, employees and other service providers for increasing a company’s value, often without an immediate cash expenditure. The available arrangements differ considerably in their tax treatment, ownership rights, administrative requirements and incentives. This article compares seven principal types of equity-based and performance awards, emphasizing their practical advantages and disadvantages.

1. Profits Interests

Profits interests have become a popular means of compensating management in private equity transactions and other businesses organized as partnerships or limited liability companies taxed as partnerships. A profits interest provides a share of future appreciation and profits, generally after existing investors have recovered their capital investment and achieved a specified return, such as a preferred internal rate of return (IRR). Unlike a capital interest, it ordinarily has no liquidation value when granted.

Tax treatment. Under Rev. Proc. 93-27, 1993-2 C.B. 343, the receipt of a qualifying profits interest is generally not taxable. The revenue procedure’s favorable treatment does not apply if (1) the interest relates to a substantially certain and predictable income stream, (2) the recipient disposes of the interest within two years, or (3) the interest is a limited partnership interest in a publicly traded partnership.

Rev. Proc. 2001-43, 2001-2 C.B. 191, extends this treatment to substantially nonvested profits interests, provided that the recipient is treated as a partner from the grant date, takes into account the distributive share of partnership income or loss, and neither the partnership nor its partners deducts the interest’s value as compensation.

Some practitioners recommend a protective election under IRC § 83(b) within 30 days after the grant of an unvested profits interest, particularly where the interest’s qualification for favorable treatment is uncertain.

A subsequent sale of a profits interest may produce long-term capital gain, subject to the applicable holding period and rules governing the character of partnership income and gain. Although the usual long-term capital gain holding period exceeds one year, Rev. Proc. 93-27 excludes dispositions within two years from its safe harbor. Further, IRC § 1061 generally imposes a three-year holding period for certain applicable partnership interests, including carried interests held by investment managers. A § 83(b) election does not eliminate the requirements of § 1061.

Advantages. Qualifying profits interests can provide substantial appreciation taxed at capital gain rates without compensation income at grant or vesting. They generally are not subject to IRC § 409A, may be structured without voting rights, and permit considerable flexibility in allocating future profits. Unlike cash compensation, a qualifying grant generally produces no corresponding compensation deduction for the partnership.

Disadvantages and administrative considerations. Profits interests involve genuine ownership and complicated partnership tax consequences. Recipients generally become partners rather than employees of the issuing partnership, receive Schedules K-1 instead of Forms W-2 for their partnership income, and may incur self-employment tax and lose eligibility for certain employee fringe benefits.

One solution is to separate the entity granting profits interests from the entity employing the recipients. For example, a parent partnership may grant profits interests while a separately classified subsidiary employs the individuals and provides wages and employee benefits. A feeder partnership may sometimes serve a similar purpose. These arrangements require careful tax structuring and additional administration.

Moreover, profits interests generally have no value unless the business appreciates sufficiently to satisfy the applicable distribution hurdles. The allocation and distribution formulas can also be complex.

Accounting. Depending on their terms and substance, profits interests may be accounted for as equity-based compensation or performance-based compensation, potentially requiring expense recognition over the service period or remeasurement.

2. Nonqualified Stock Options (NQSOs)

A nonqualified stock option gives the recipient the right to purchase employer stock at a specified exercise price during a stated period. To qualify for the customary stock-right exemption from IRC § 409A, the exercise price generally must equal or exceed the stock’s fair market value on the grant date, and the option must satisfy other regulatory conditions.

Tax treatment. NQSOs generally produce no taxable income at grant or vesting. Upon exercise, the excess of the stock’s fair market value over the exercise price is ordinary compensation income, generally subject to employment taxes. The employer ordinarily receives a corresponding tax deduction. Subsequent appreciation is taxed as capital gain when the stock is sold, with long-term treatment if the applicable holding period is satisfied.

IRC § 83(i) permits certain employees of qualifying private corporations with broad-based equity programs to defer income recognition on qualifying stock acquired through option exercises for up to five years. The election is subject to substantial restrictions and generally is unavailable to senior executives and certain other employees.

Advantages. NQSOs reward appreciation without an employer cash expenditure at grant. Recipients generally may decide when to exercise, and options may be awarded to employees, directors and independent contractors. They can also be granted before employment begins, unlike incentive stock options.

Disadvantages. Options become economically unattractive when the share price falls below the exercise price. Exercise may require substantial cash, although cashless exercise arrangements may be available. Recipients incur ordinary income tax on exercise, potentially before receiving sale proceeds, and privately held companies face valuation and liquidity challenges.

Accounting. Option grant-date fair value, generally determined using an option-pricing model, is recognized as compensation expense over the applicable vesting period.

3. Incentive Stock Options (ISOs)

Incentive stock options provide more favorable tax treatment than NQSOs but are subject to the statutory requirements of IRC §§ 421 and 422.

ISOs may be granted only to employees of qualifying corporations. The exercise price must be at least fair market value when granted, or 110% of fair market value for certain shareholders owning more than 10% of the corporation. The plan must receive shareholder approval, and options must generally be exercised within ten years after grant, reduced to five years for 10% shareholders.

The aggregate grant-date fair market value of stock underlying ISOs first exercisable by an employee in any calendar year is limited to $100,000. Options exceeding the limit are treated as nonqualified options to that extent.

Tax treatment. Unlike an NQSO, an ISO generally produces no regular federal income tax upon exercise, although the spread may be included for alternative minimum tax (AMT) purposes. If the employee holds the shares for more than one year after exercise and more than two years after grant, the appreciation generally qualifies for long-term capital gain treatment.

The employer ordinarily receives no compensation deduction on a qualifying disposition. However, if the employee disposes of the shares before satisfying the holding periods, part of the gain may be treated as ordinary compensation income, with a corresponding employer deduction.

Advantages and disadvantages. ISOs can provide substantial capital gain benefits without ordinary income tax at exercise. However, the AMT exposure, holding periods, statutory limitations and absence of an employer deduction reduce their attractiveness. Recipients generally must remain employed until no more than three months before exercise, subject to statutory exceptions. ISOs also cannot be issued with respect to ownership interests in an entity taxed as a partnership.

The accounting treatment generally parallels that of NQSOs.

4. Restricted Stock Awards

Restricted stock consists of actual company shares transferred to an employee or other service provider, subject to forfeiture until specified vesting conditions are satisfied. Vesting generally depends on continued service, performance goals or both.

Unlike stock options, restricted shares retain value even if the stock price declines. Recipients may also receive voting and dividend rights from the grant date, depending on the award terms.

Tax treatment. Under IRC § 83(a), restricted stock ordinarily is not taxable upon grant but becomes taxable as ordinary compensation income when substantially vested. The taxable amount generally equals the fair market value of the shares, less any amount paid by the recipient. The employer receives a corresponding deduction, subject to applicable limitations.

Alternatively, the recipient may make an election under IRC § 83(b) within 30 days after the transfer, recognizing the value of the stock at grant rather than vesting. Subsequent appreciation may then qualify for long-term capital gain treatment upon sale.

The principal disadvantage of a § 83(b) election is that the recipient pays tax at grant without assurance that the shares will vest or retain their value. If the stock is later forfeited, the previously paid income tax generally is not recoverable.

Advantages. Restricted stock provides immediate equity ownership, greater downside value than options and potential capital gain treatment on appreciation following an effective § 83(b) election. Actual transfers of restricted stock generally are outside IRC § 409A.

Disadvantages. Tax at vesting may create a liquidity problem, particularly in private companies. Voting and dividend rights may also complicate the company’s ownership arrangements, and restricted shares cause actual shareholder dilution.

Accounting. Restricted stock generally is accounted for as equity-based compensation, with expense recognized over the requisite service period.

5. Phantom Stock and Restricted Stock Units (RSUs)

Phantom stock and restricted stock units provide compensation measured by the value of company shares without transferring actual ownership at grant. Both generally represent unfunded, unsecured contractual promises to make a payment at a future date.

RSUs typically settle in employer stock, while phantom stock ordinarily settles in cash. Vesting generally depends on continued service, performance goals or a combination of both.

Tax treatment. Neither arrangement ordinarily produces taxable income at grant. The recipient generally recognizes ordinary compensation income when cash or shares are delivered, and the employer ordinarily receives a corresponding deduction. Because no property is transferred at grant, a § 83(b) election is unavailable.

Phantom stock and RSUs must comply with or qualify for an exemption from IRC § 409A. One common approach is to require settlement within the short-term deferral period, generally no later than 2½ months after the end of the applicable taxable year in which the award is no longer subject to a substantial risk of forfeiture. Awards with later settlement dates must generally comply with § 409A’s restrictions on payment timing and acceleration.

Employment taxes may arise at vesting even when settlement is deferred, under the special timing rules for nonqualified deferred compensation.

Advantages. Phantom stock and RSUs provide incentives tied to company value without requiring the recipient to purchase shares. Phantom stock is particularly useful for closely held businesses that wish to reward employees without admitting additional shareholders or relinquishing voting control. Income tax generally is postponed until settlement.

Disadvantages. Payments are taxed as ordinary compensation rather than capital gain. Participants generally do not obtain shareholder rights before settlement, although dividend equivalents may be provided. IRC § 409A also limits flexibility in determining payment dates and accelerating distributions.

Accounting. Equity-settled RSUs generally involve grant-date fair-value accounting, while cash-settled phantom awards may require periodic liability remeasurement.

6. Stock Appreciation Rights (SARs)

Stock appreciation rights give recipients the right to receive the increase in the value of specified company shares between grant and exercise, ordinarily payable in cash or stock.

SARs are economically similar to stock options, but recipients need not pay an exercise price to obtain the appreciation.

Tax treatment. A SAR generally is not taxable at grant or vesting. Upon exercise or settlement, the amount received is ordinary compensation income, ordinarily giving rise to a corresponding employer deduction.

SARs may qualify for an exemption from IRC § 409A if the exercise price or base value is at least the underlying stock’s fair market value on the grant date, the underlying stock satisfies the service-recipient-stock requirements, and the award does not provide an additional deferral feature.

Advantages. SARs reward stock appreciation without requiring recipients to finance an exercise price or become shareholders. Cash-settled SARs also avoid issuing additional shares.

Disadvantages. Like stock options, SARs provide limited incentives when company value does not appreciate. Payments are taxed as ordinary compensation, and the employer may incur a substantial cash obligation upon settlement. Valuation and § 409A compliance can be particularly important for private companies.

Accounting. SAR expense generally is recognized over the vesting period, with additional remeasurement required for cash-settled liability awards.

7. Performance Awards and Bonuses

Performance awards provide cash or stock compensation upon attainment of specified individual, business-unit or company-wide goals. The terms generally establish eligibility, performance measures, threshold and target awards, and treatment upon termination of employment or a change in control.

Performance awards are particularly useful where an employer wishes to reward specific business results, such as profitability, revenue growth, investment returns or other measurable objectives, without necessarily granting actual equity.

Tax treatment. Performance bonuses generally are taxable as ordinary compensation when paid, with a corresponding employer deduction subject to applicable limitations.

Awards that are paid within the short-term deferral period generally are exempt from IRC § 409A. Awards involving longer deferrals must comply with § 409A, including its requirements governing payment events and restrictions on acceleration. Employment taxes may apply at vesting even if payment is deferred.

Advantages. Performance awards can be tailored to specific business objectives, encourage accountability and avoid issuing additional equity. They also may be structured to balance annual and long-term performance goals.

Disadvantages. Performance standards and payout calculations can become complicated, particularly where several financial or operational measures are involved. Awards may lose their retention value if the performance goals appear unattainable. Long-term arrangements also require careful § 409A drafting.

Accounting. Cash performance bonuses generally are accrued when payment becomes probable and reasonably estimable. Equity-settled performance awards ordinarily are accounted for under the applicable share-based compensation rules.

Conclusion

The appropriate form of equity-based compensation depends on the employer’s ownership structure, tax objectives, liquidity, willingness to dilute existing shareholders and desired incentive.

Profits interests can provide particularly favorable tax treatment for businesses taxed as partnerships, but create ownership and administrative complications. NQSOs and SARs reward future appreciation without transferring immediate ownership. ISOs offer potentially favorable capital gain treatment but impose significant statutory restrictions. Restricted stock provides actual ownership and the possibility of capital gain treatment through a § 83(b) election. Phantom stock and RSUs provide equity-linked incentives without immediate ownership, while performance awards permit employers to target particular business objectives.

In selecting among these arrangements, the tax consequences to the recipient and employer, the requirements of IRC §§ 83 and 409A, and the practical costs of administration should be considered together.

See https://drive.google.com/file/d/19eBhlDz7nz0BCBKSy57Uh3lTmbhl-6zM/

Categories
Blog

More MEPs – Less Bad Apples

                                             Multiple Employer Plans under the SECURE Act of 2019 
                                                and Proposed Regulations re  Exemption from One Bad Apple Rule

Charles C. Shulman, Esq.,
Teaneck, NJ
201-357-0577
cshulman@ebeclaw.com

Multiple Employer Retirement Plan Generally

Multiple employer plans, i.e., plans that are maintained by more than one employer that are not collectively bargained, are subject to the more restrictive requirements under Code §413(c). Under Code §413(c), a multiple employer plan is treated as if all the employees were employed by a single employer for the following purposes: age and service requirements of Code §410(a), the exclusive benefit rule of Code §401(a)(2); the vesting rules of Code §411; and the limit on contributions and benefits under Code §415. For other purposes, multiple employer plans are treated as if each employer were maintaining a separate plan, for example: the participation requirements of Code §410(b); the nondiscrimination requirements of Code §401(a)(4); the ADP and ACP tests of Code §§401(k) and 401(m); the vesting requirements upon termination or partial termination; the funding and deductions limits for plans established after 1988; the limit on annual compensation of Code §401(a)(17) and the top-heavy rules of Code §416.  Code § 413(c); Treas. Reg. §1.413–2 and related regulations.

Allowing Unrelated Employers to form a Valid ERISA Multiple Employer Plan (referred to by the SECURE Act of 2019 as a Pooled Employer Plan.

Open MEPs as Separate Employee Benefit Plans Under Pre-SECURE Act Law. Where a service provider sets up a retirement plan for multiple “unrelated” employers with no connection to each other and no connection to the service provider other than the provision of retirement services, the DOL had ruled in a 2012 advisory opinion that this arrangement was not a single multiple-employer plan under ERISA but rather separate employee benefit plans for each employer.

Pre-SECURE Act Efforts to Expand MEPs. There had been efforts even prior to the SECURE Act of 2019 (discussed below) to expand access to workplace retirement plans by small employers, who may not wish to bear the difficulty or expense of setting up their own plans, by allowing such employers to join with certain other employers in a multiple employer defined contribution plan (“MEP”).  

Two significant impediments have made setting up MEPs difficult. The first impediment has been that a MEP may be treated by the DOL as separate plans for each employer, especially for non-affiliated employers, requiring separate reporting and disclosure. (The second impediment is the one bad apple rule discussed below.) The DOL in 2019 issued guidance in DOL Reg. § 2510.3-55 to address the above concerns regarding MEPs, with expanded rules as to when separate employers who participate in a defined contribution plan would be considered a single ERISA plan rather than multiple ERISA plans.

SECURE Act of 2019 Expansion of Open MEPs (PEPs). The SECURE Act of 2019, P.L. 116-94 (Dec. 20, 2019), expands the use of multiple employer plans by allowing totally unrelated companies to use a single shared defined contribution “pooled employer plan” (PEP), provided the third-party plan administrator is a “pooled plan provider” that has registered with the DOL and acknowledges that it is a named fiduciary of the plan.

The SECURE Act defines ”pooled employer plan” in new ERISA § 3(43)(A) as a qualified defined contribution plan or IRA with two or more employers that meets certain additional requirements. Employers in the pooled employer plan need not have a common non-plan-related interest. The plan must designate a pooled plan provider, provide that there will be no unreasonable fees for ceasing participation and to provide for certain disclosure.  Note that the Internal Revenue Code does not use the term “pooled employer plan,” but rather refers to a section 413(e) multiple employer plan that has a pooled plan provider.

“Pooled plan provider” is defined in ERISA § 3(44)(A) as (i) a named fiduciary, and plan administrator responsible to perform all administrative duties reasonably necessary to ensure that the plan meets the qualification requirements of Code § 401(a) (or IRA that meets the requirements of Code § 408) and other ERISA requirements, and requiring participating employers to takes actions necessary for the plan to meet the such requirements; (ii) which must register with the DOL as a pooled plan provider; (iii) which must acknowledge its status as a named fiduciary and as the plan administrator; and (iv) which is responsible for ensuring that all persons who handle plan assets or are plan fiduciaries are bonded in accordance with ERISA § 412.

DOL November 2020 Regulations on Registration Requirement for Pooled Plan Providers. The DOL issued regulations in November, 2020, Prop. DOL Reg. § 2510.3-44, effective November 16, 2020, pursuant to ERISA § 3(44)(A)(ii), for registration required 30 to 90 days before beginning operations as a pooled plan provider with certain information about the pooled plan provider on DOL Form PR. Reporting on Form PR is also required if there are changes to the initially reported information or any government agency action or finding of fraud or criminal conduct relating to the assets or the operation of the plan. In addition, a final Form PR is filed on termination or cessation of operations of the pooled plan provider. Form PR must be filed electronically. DOL Reg. § 2510.3-44; Instructions to DOL Form PR.

Increased maximum amount of bond for pooled employer plan. With regard to a fiduciary or person holding assets of a pooled employer plan, the maximum bond amount under ERISA § 412(a) as amended by the SECURE Act of 2019 is $1 million instead of $500,000.

Form 5500 reporting. Form 5500 for all multiple employer plans must include a list of the employers in the plan, a good faith estimate of the percentage of total contributions made by each employer, and the aggregate account balances attributable to each employer.  For pooled employer plans, the Form 5500 now requires identifying information for the pooled plan provider. In addition, the limited scope audit exemption for plans with fewer than 100 participants, which also avoids the need for plan audited financial statements, is modified by the SECURE Act of 2019 to provide that simplified reporting can be used for multiple employer plans that cover fewer than 1,000 participants if no single employer in the plan has 100 or more participants. 

Effective date. These provision applies to plan years beginning after December 31, 2020.

Multiple Employer Plans – “One Bad apple” rule and MEPs Exception

Background. As referenced above, the second impediment to establishing and maintaining MEPs has been the unified-plan rule (also called the “one bad apple” rule) under which if one employer’s portion of a multiple employer plan is disqualified the entire multiple employer plan will be disqualified. See, e.g., Treas. Reg. § 1.413-2(a)(3)(iv). The IRS in 2019 gave some relief in Prop. Treas. Reg. § 1.413-2, which would permit an exception to the one bad apple rule if one employer refuses to correct its qualification errors or fails to provide information to the plan administrator regarding a potential disqualification. 

Further Relief in SECURE Act from the One Bad Apple Rule Under Code § 413(e). The SECURE Act of 2019 added Code § 413(e), which provides relief for multiple employer qualified plans or multiple SEP/SIMPLE IRA plans of unrelated employers administered by a pooled plan administer from the ”one bad apple rule” (also referred to as the uniform rule), that the entire plan will not be disqualified merely because one or more participating employers fail to take actions required by Code §§ 401(a) or 408(a) with respect to the qualified plan or IRA plan. Such relief will only apply if the plan provides that plan assets attributable to employees of the noncompliant employer will be transferred to a plan maintained only by that employer or to an individual tax-favored plans or IRAs and the noncompliant employer would be liable for any plan liabilities due to noncompliance. Code § 413(e) defines “pooled plan provider” substantially the same as ERISA § 3(44).  The DOL and Treasury are directed it issue guidance regarding these provisions. These provision applies to plan years beginning after December 31, 2020.

2022 Proposed Regulations Regarding Exemptions from the One Bad Apple Rule for Section 413(e) Defined Contribution Plans or IRA Plans

Proposed Regulations. On March 28, 2022 the IRS issued proposed Treas. Reg. § 1.413-3 regarding the exception to the one bad apple (uniform plan) rule under Code § 413(e) for multiple employer defined contribution plans or IRA plans that are maintained by employers that have a common interest (other than the sharing of the plan) or  have a common pooled plan provider (a “section 413(e) plan”).

Conditions. For the 413(e) plan to be entitled to the exception from the one bad apple rule, the following conditions must be met:  (i) the section 413(e) plan must describe the first, second and final notices that will be sent for a participating employer failure, the actions the section 413(e) plan administrator will take if  an unresponsive participating employer does not either take appropriate remedial action or initiate a spinoff, and that if the unresponsive employer does not act by the 60 days after the final notice, participants of that employer will become fully vested in their accounts;  (ii) the section 413(e) plan administrator must satisfy the notice requirements regarding the participating employer failure, implement the plan spinoff if initiated by the unresponsive employer and take the actions set forth in the regulations if the unresponsive participating employer fails to take appropriate remedial action or initiate a spinoff by 60 days after the final notice; and (iii) if the section 413(e) plan has employers that do not have a common interest and a “pooled plan provider” is required, the pooled plan provider must perform substantially all of the administrative duties that are required of the pooled plan provider under the regulations, as stated below. Prop. Treas. Reg. § 1.413-3(a)(2).

Pooled Plan Provider. A pooled plan provider is a person (an individual or entity) that: (i) registers as a pooled plan provider with the DOL pursuant to ERISA; (ii) is designated by the plan and acknowledges that it is a named fiduciary and the plan administrator; (iii) ensures that those who handle assets or are fiduciaries are bonded in accordance with ERISA § 412. A pooled plan provider must: (i) perform all administrative duties reasonably necessary to ensure that the plan remains qualified/in compliance with the Code and ERISA; (ii) monitor compliance with the terms of the plan, the Internal Revenue Code and ERISA; (iii) maintain accurate data and up-to-date participant and beneficiary information; (iv) conduct nondiscrimination, minimum coverage and top-heavy tests under the Internal Revenue Code, as applicable; (v) process all employee investment changes, loans and distribution transactions; (vi) satisfies reporting and notice requirements of the Code and ERISA; and (vii) amends the plan for all statutory-required changes.  Prop. Treas. Reg. § 1.413-3(a)(3).

Certain Section 1.413-3 Definitions.  (i) “Participating employer failure” means failure to provide information or a failure to take action required of it by the regulations. (ii) “Section 413(e) plan” is a defined contribution plan IRA plan that either (A) has a common interest other than having adopted the plan or (B) has a pooled plan provider. (iii) “Section 413(e) plan administrator” means a plan administrator designated by the section 413(e) plan. (iv) “Unresponsive participating employer” means a participating employer that has a participating employer failure. Prop. Treas. Reg. § 1.413-3(a)(4).

Notices. A section 413(e) plan administrator must provide a “first notice” to an unresponsive participating employer describing its failure, the actions the employer must take to remedy the failure, and that employer’s option to initiate a spinoff of a separate plan of the unresponsive employer, and consequences if the employer does not comply.  If, after 60 days, the employer does not take appropriate remedial action or initiate a spinoff, the section 413(e) plan administrator must provide a “second notice” which must state that if within 60 days the unresponsive participating employer does not takes appropriate remedial action or initiate a spinoff, then a “final notice” describing the participating employer failure and the consequences of not correcting the failure will be provided to participants employed  by the employer, their beneficiaries and the DOL. A “final notice” provided within 30 days to participants employed the unresponsive participating employer and their beneficiaries and to the Office of Enforcement of the DOL EBSA must specify the final deadline for an unresponsive participating employer to take remedial action or initiate a spinoff. Prop. Treas. Reg. § 1.413-3(b).

Final Deadline. The final deadline for an unresponsive participating employer to take appropriate remedial action or plan spinoff is 60 days after the final notice. Prop. Treas. Reg. § 1.413-3(c)(1).

Appropriate Remedial Action. If the participating employer’s fails to provide required information, appropriate remedial action is by providing the data, documents, or other information requested by the section 413(e) plan administrator. If the participating employer fails to take required action, appropriate remedial action is by taking all actions requested by the section 413(e) plan administrator, such as making corrective contributions. Prop. Treas. Reg. § 1.413-3(c)(2).

Implementing an Employer-Initiated Spinoff. An unresponsive participating employer can initiate a spinoff by directing the section 413(e) plan administrator to spin off the amounts attributable to its employees to a separate qualified plan or IRA plan maintained it. The section 413(e) plan administrator must complete the spinoff as soon as reasonably practicable, which is deemed to be met if the spinoff is completed within 180 days from when the spinoff was initiated. Prop. Treas. Reg. § 1.413-3(d)(2). 

Required Actions Following an Employer’s Failure to Meet the Deadline – Stop Contributions, Fully Vest Participants and Allowing Each Affected Participant an Individual Rollover to Another Qualified Plan or IRA. If by the time of the final deadline discussed above, the participating employer fails to take appropriate remedial action or initiate a spinoff, then as soon as reasonably practicable, the section 413(e) plan administrator must (i) stop accepting contributions from the unresponsive participating employer and its employees; (ii) give notice that no further contributions will be made and that additional information will follow; (iii) fully vest the employees; and (iv) give the each employee an option for an individual rollover to a qualified plan or IRA. Prop. Treas. Reg. § 1.413-3(e)(1) & (2).

As stated in the previous paragraph, an election must be given to employees of an unresponsive participating employer (following a failure to meet the deadline to take remedial action or initiate a spinoff) to have their account rolled over directly to another qualified plan or an individual IRA, or alternatively the participant’s account will remain in the original section 413(e) plan. If no election is made, the default is to remain in the section 413(e) plan. Prop. Treas. Reg. § 1.413-3(e)(3). The option to remain in the plan does not exist if the participant’s account is less than $200, in which case such amount will be mandatorily distributed. § 1.413-3(e)(4).  Also, if there is a required minimum distribution under IRC § 401(a)(9), such amount must be distributed and cannot be rolled over or remain in the plan. § 1.413-3(e)(4).  

Reliance Permitted Beginning March 28, 2022: These proposed regulations may be relied upon beginning March 28, 2022.

Comments

It is not entirely clear to what extent pooled plan providers can delegate their functions to outside third-party administrators, e.g., record-keepers.

The proposed rules only apply to defined contribution plans and it is unclear if similar rules will be adopted for  defined benefit MEPs.

A public hearing on the proposed regulations was set for June 22, 2022.

The above proposed regulations, by implementing the unified plan rule for unrelated-employer MEPs, should eliminate a potential barrier to an employer joining such MEPs.

See article at https://drive.google.com/file/d/1xNBLDko4GJny5VKLkK0aN-lO-JtGVEzd/

Categories
Blog

Profits Interests

 A Primer on Profits Interests

Charles C. Shulman, Esq.,
Teaneck, NJ, 201-357-0577
cshulman@ebeclaw.com

Profits interests have become an increasingly popular type of equity-based award if the entity is taxed as a partnership, as they avoid income tax or FICA tax on grant and vesting, and yield long-term capital gains on sale if certain requirements are met.

      a.   Description
            i.    A profits interest is an interest in the value of a partnership or LLC taxed as a partnership. It has upside potential but no downside protection.

            ii.   The granting of profits interests has become a preferred way of compensating management in buyouts or as partnership incentives.

            iii.   Profits interests may be structured as a separate class of ownership interests.

            iv.  Profits interests typically provide a share of profits only once the original LP investors have received a return of their full capital investment and a certain rate of return (e.g., IRR).

            v.   The profits interests must be held for a certain period to receive favorable tax treatment, as discussed below.

      b. Tax Treatment of Profits Interests

            i.    Revenue Procedure 93-27 provides that the IRS will treat the receipt of a profits interest as non-taxable if the following conditions are met: (a) the profits interests do not relate to a substantially certain and predictable stream of income from partnership assets, (b) for two years after receipt of the profits interest the partner does not dispose of the profits interest, and (c) the partnership or LLC is not a publicly traded partnership as defined in Internal Revenue Code §7704(b). In addition, the profits interest cannot be a capital interest, which, according to Proc. 93-27 means that if the partnership’s assets would be sold at fair market value, and the proceeds would be distributed in a complete liquidation of the partnership, the profits interest holder would not receive a share of the proceeds.

            ii.   Rev. Proc. 2001-43 provides that even if the profits interest is nonvested at the time of grant, the profits interests will be non-taxable at the time of grant and at vesting, provided that: (a) the partnership treats the recipient as a partner from date of grant, and the partner must take into account its distributive share of partnership income or loss, and (b) the partnership and other partners do not deduct such amounts as wages.

            iii.   Some make a Code § 83(b) “protective” election on nonvested profits interests so that even if they are found to be taxable profits interests, there would be no tax in any event until vested.

            iv.  Upon the sale or liquidation of the profits interest (after the two-year hold period), the proceeds are taxed at the lower long-term capital gains rate.

      c.   Holding Periods for Profits Interests

            i.    Generally long-term capital gains require a one-year holding period. However, with regard to profits interests, Rev. Proc. 93-27 requires that the profits interest be held for at least a two-year period.

            ii.   If there is a Code § 83(b) protective election, there may not be a need for a two-year holding period, since even a capital interest with a § 83(b) election can utilize long-term capital gains rates if held for one year or longer.

            iii.   There may be a three-year holding period if the partnership owns real estate for rental or investment, since Code § 1061, enacted by the Tax Cuts & Jobs Act of 2017 and effective in 2018, in an effort to clamp down on carried interest use of long-term capital gains tax rates for fund managers, provides that “applicable partnership interests” which includes professional investors as well as those developing real estate for rental or investment, have an increased holding period for long-term capital gains treatment for three years instead of one year.  In this regard, a § 83(b) election would not help to shorten the period.

      d.   Setting Up Separate Entities so that Employer Pays Wages and Partnership Distributes Profits Interests.

            i.    Grantees of profits interests would ordinarily become partners of the entity granting the profits interests with taxes based on Form K-1 partnership returns, and could not be both partners and employees, and therefore the grantees would lose the ability to participate in the cafeteria plan or other flex benefits and would owe self-employment social security tax. 

            ii.   To allow the grantees to continue to be employees, often a subsidiary of the partnership can serve as the employer, while the main partnership grants the profits interest.  For example, the main partnership grants the profits interest; an Employer LLC subsidiary (typically a partnership) is set up as the employer entity that pays wages and employee benefits (with a services agreement with the main partnership); and there is typically a need for a holding company, Employer Holdings taxed as a corporation, which needs to own a small amount (e.g., 1%) of the Employer LLC subsidiary for tax purposes so that the Employer LLC partnership is regarded as a separate entity.    

            iii.   Alternatively, sometimes the profits interests are passed through a feeder entity to the grantees so that they can still be employees of the entity.

            iv.  Keep in mind that setting up these structures does involve extra work to set up and administer.

      e.   Advantages of profits interests                 

            i.    Non-taxability at grant (or on vesting) until the grantee ultimately sells or liquidates the profits interests, and then generally only at the long-term capital gains rate.

            ii.   As equity, the profits interest should not be subject to Code § 409A, and instead it is governed by § 83 principles.

            iii    Profits interests can have a flexible payout.

            iv.  Profits interests can be granted without voting rights.

      e.   Disadvantages of profits interests

            i.    Profits interests must be held at least two years to receive favorable tax treatment (or likely one year if a § 83(b) election is made).

            ii.   The employer will not receive any deduction from the profits interest.

            iii.   The payout formulas are often complicated to administer.

            iv.  There is no downside protection if there are not sufficient profits, and in this way profits interests are more similar to stock options than to restricted stock.

            v.   Grantees may become partners instead of employees of the entity granting the profits interests unless separate structures are set up to separate the employer from the entity granting the profits interests (see above).

      f.    Accounting Treatment for Profits Interests – Profits interests, depending on the facts, would be treated for accounting purposes as either performance compensation or stock compensation. Performance compensation costs may be expenses when the payment is probable and reasonably estimable. Stock compensation is expensed based on its fair value over the period of service (but sometimes revalued each accounting period).

=============================

As
discussed in my earlier post on Profits Interest at https://ebeclaw.com/2022/03/profits-interests.html 
,
profits interests have become an increasingly popular type of equity-based
award if the entity is taxed as a partnership, as they avoid income tax or FICA
tax on grant and vesting, and yield long-term capital gains on sale if certain
requirements are met. However, in 2017 this was limited 
in
the case of profits interests (carried interest) for professional investors
 and
real estate development for rental or investment
 to where the holding period is
three years. A 2020 legislative proposal in the pending Inflation Reduction Act
to increase the holding period for such carried interest from three years
to five years and to only begin only once substantially all the
partnership interest subject to IRC § 1061 are acquired by the partnership
. However, in further negotiations this carried interest tax proposal is
apparently being taken out of the legislation. 

Pre-2017 Holding Period for Profits Interests – Two Years from Grant and One Year from Vesting. Prior to the enactment of the Tax Cuts & Jobs Act of 2017, generally long-term capital gain treatment for profits interest would require the general one-year holding period requirement (from the date the profits interests are vested). In addition, Rev. Proc. 93-27 would require that the profits interests be held for at least two-years after the date of grant.

Extended Holding Period for Professional Investors and Real Estate Investment to Three Years Under TCJA of 2017. Legislative changes imposed by the Tax Cuts & Jobs Act of 2017 (effective January 1, 2018) enacted a new IRC § 1061, which imposes a three-year holding period (instead of one year for ordinary capital gains) for an “applicable trade or business,” if the partnership owns real estate for rental or investments, since IRC § 1061, enacted by the Tax Cuts & Jobs Act of 2017 and effective in 2018, in an effort to clamp down on “carried interest” use of long-term capital gains tax rates for fund managers, provides that “applicable partnership interests” which includes professional investors as well as those developing real estate for rental or investment (IRC § 1061(c)(2)), have an increased holding period for long-term capital gains treatment for three years instead of one year. IRC § 1061(a).

2022 Proposed Legislation to Further Extend Holding
Period for
 Such Carried Interest to
Five Years, was Removed from the Bill to Win Approval from Sen. Krysten Sinema. 
Further legislative changes had been proposed in the Inflation Reduction
Act in July 2022, H.R. 5376, to amend IRC 
§ 1061 in
the following ways: (i) the holding period for “applicable partnership
interests” which, under IRC 
§ 1061(c)(2),
includes carried interest for professional investors (e.g., 
private equity firms and hedge funds) and real estate development for rental or
investment, would be increased from three years
to five years (except with respect to taxpayers with adjusted gross income of
less than $400,000); (ii) the five-year holding period would begin only once
substantially all the partnership interest subject to 
§ 1061 are
acquired by the partnership; and (iii) the holding period would now apply not
just to profits interest but also to other income taxed as long-term capital
gains, including qualified dividend income included in net capital gain for
purposes of IRC § 1(h)(11), gain from the sale of active business assets under
IRC § 1231 and regulated futures contracts subject to IRC § 1256. However, it
has now been reported on August 4, 2022 that Democrats are revising their
Inflation Reduction Act in order to will approval from Senator Kyrsten Sinema
(D. Arizona), which, among other things, would drop the proposed tax increase
on carried-interest income.

Categories
Blog

Successor Liability for Pension and Other ERISA Obligations


One of the murky but interesting aspects of ERISA law
has been the extent to which liability under ERISA will carry over to
successors who purchase the assets rather than the stock of the business. 

The general common law rule is that a company that
purchases assets of another company is not responsible for the seller’s
liabilities, except (i) where the purchaser expressly or impliedly agrees to
assume the seller’s liabilities; (ii) where the transaction is a “de facto
merger” (looking at continuity of ownership, enterprise, and management); (iii)
where the purchaser corporation is a “mere continuation” (merely a restructured
or reorganized form of seller’s corporate entity) of the seller; and (iv) where
the transfer of assets is for the fraudulent purpose of escaping liability from
the seller’s debts. 

Case law has expanded successor liability for certain
obligations under ERISA in certain circumstances. Specifically, a number of
cases have found successor liability for pension obligations if there is
“continuity of operations”, as well as knowledge, even if this is no
“continuity of ownership.”  

I recently authored an article in the Tax Management
Compensation Planning Journal – at 
https://ebeclaw.com/2022/02/successor-liability-for-pension-and.html  or https://tinyurl.com/erisa-successor-liability – which explores the current state of the law regarding successor liability
under ERISA and other employment contexts. The article reviews seminal and
recent case law on this issue in the areas of the multiemployer pension withdrawal
liability contexts, single-employer pension plan termination liability,
executive retirement plans, retiree health liability, ERISA fiduciary liability
(according to some courts), labor law and unfair labor practices, and
employment discrimination contexts. 

If you have any questions, please contact me at the
address or telephone below.

Thanks

Charlie Shulman, Esq.

mailto:cshulman@ebeclaw.com
 

201-357-0577


Article at https://ebeclaw.com/2022/02/successor-liability-for-pension-and.html
 or at https://tinyurl.com/erisa-successor-liability 

Categories
Blog

Successor Liability for Pension and Other ERISA Obligations (Compensation Planning Journal)


Successor Liability for Pension and
Other ERISA Obligations

49
Compensation Planning Journal No. 9 p. 32 

Charles C. Shulman, Esq.*

https://drive.google.com/file/d/1Dqz-DUXo2DinSEth5jl3srUU1GB4ipCZ/

One of the murky but interesting aspects of ERISA law —
which has been revisited from time to time by the federal courts — has been the
extent to which liability under ERISA will carry over to successors who
purchase the assets rather than the stock of the business. This article
explores the current state of the law regarding successor liability under
ERISA.

GENERAL COMMON-LAW RULES OF
SUCCESSOR LIABILITY – CONTINUITY OF OPERATIONS AND CONTINUITY OF OWNERSHIP
 [S2]
[UC]

The general common law rule is that a company that
purchases assets of another company is not automatically responsible for the
seller’s liabilities.[1] There are generally four exceptions—where successor
liability will apply to a purchaser of all or substantially all of the assets
of a seller.

Express or Implied Assumption of Liabilities

The first exception is where the purchasing company
expressly[2] or impliedly[3] agrees to assume the selling company’s liabilities.

De Facto Merger

The second exception is where the transaction amounts
to a “de facto merger”—i.e., buyer’s existing business and target business are
deemed like a merger  ̶ looking to four factors which favor such a
finding: (i) continuity of ownership (e.g., purchaser company pays for the
assets with stock of the purchaser), (ii) continuity of the business
enterprise, evidenced by continuity of management, personnel, physical
location, assets and general business operations, (iii) dissolution of seller,
and (iv) purchaser assuming obligations necessary for uninterrupted
continuation of normal business operations of seller.[4] Many cases require the continuity-of-shareholders prong
to find a de facto merger.[5]

Mere Continuation of Seller Entity.

The third exception is where the purchaser corporation
is a “mere continuation” of the seller, i.e., merely a restructured or
reorganized form of seller’s corporate entity and not simply a continuation of
the business operation. This excep­tion is aimed at owners and directors who
may dissolve one company and begin another to avoid debts and liabilities.
Factors include: (i) common identity of officers, directors and shareholders in
the selling and purchasing corporations (continuity of ownership or corporate
structure), (ii) continuity of business operations, (iii) cessation of ordinary
business by seller, and (iv) inade­quate consideration paid for assets.[6] Common identity of officers, directors and share­holders
is the key element to finding mere continuation.[7] This “mere continuation” exception is very similar to the
“de facto merger” exception and they are sometimes treated together in case
law.[8] Note that the “de facto merger” and “mere continuation” tests
above are narrower than the “continuity of operations” condition for pension
successor liability under the Artistic Furniture line of cases
discussed below, in that de facto merger and mere continuation generally
require continuity of ownership, which is not the case in the pension successor
liability cases, where continuity of operations typically suffices.

Fraudulent Transfer

The fourth exception is where the transfer of assets is
for the fraudulent purpose of escaping liability for the seller’s debts.[9]

Product-Line Exception 

A small number of jurisdictions, including California
and New Jersey, recognize an additional, more expansive exception under which
successor liability might attach to an asset purchaser—the so-called “product
line” doctrine.[10]

Tax Liability on Successor

Section 6901[11] sometimes imposes tax on a successor. Specifically §6901
allows the IRS to assess and collect taxes from the transferee of
property in the same manner as it does in the case of the transferor entity
that originally incurred the tax liability.[12]

Free and Clear Bankruptcy Asset Sale

Bankruptcy Code §363, 11 U.S.C. 363, allows a
bankruptcy trustee to sell the property of the bankruptcy estate “free and
clear” of any interest in the property.[13]

BROADENED APPLICATION OF
SUCCESSOR LIABILITY IN ERISA MULTIEMPLOYER PENSION OBLIGATIONS

Broadened
Application of Successor Liability for ERISA Obligations

Minimum funding pension obligations, Title IV
termination liability, multiemployer withdrawal liability and other pension
liabilities would seem to be treated like any other preexisting obligation that
unless assumed by the buyer — or unless the common law exceptions for successor
liability apply — the buyer of assets would not be liable for the seller’s
obligations.

However, case law has expanded successor liability for
certain obligations under ERISA in certain circumstances. Specifically, a
number of cases have found successor liability for pension obligations if there
is continuity of operations, as well as knowledge, even if this is no
continuity of ownership, while in the non-ERISA context successor liability
also requires continuity of ownership.

A number of cases — including circuit and district
court decisions in the Seventh, Sixth, Second, Third, and Ninth Circuits — have
found successors in asset purchases to be liable for the predecessors’ pension
obligations under ERISA even where the general common law exceptions for
successor liability would not ordinarily apply.

Most of the cases discussed below are in the
multiemployer pension withdrawal liability contexts, but other cases expand
successor liability in the context of single-employer pension plan termination
liability, executive retirement plans, retiree health liability, ERISA
fiduciary liability (according to some courts), labor law and unfair labor
practices, and employment discrimination contexts.

ERISA
Successor Liability— Seventh Circuit 1990 Artistic Furniture Case Regarding
Unpaid Contributions to Multiemployer Pension Plan— Continuity of Business
Operations and Notice.

In Upholsterers’ International Union Pension
Fund v. Artistic Furniture of Pontiac
,  the Seventh Circuit held that
under ERISA a purchaser of assets could be liable for delinquent pension
contributions owed by the seller to a multiemployer pension fund maintained by
the union even when the common-law successor liability exceptions do not apply;
provided, that: (i) there is sufficient evidence of continuity of operations
and (ii) the purchaser had knowledge of the liability of the seller.[14] There would be no requirement for continuity of
ownership, as there are under the common law exceptions for successor
liability.

In Artistic Furniture, the old employer,
Pontiac Furniture, ceased making contributions to a multiemployer pension fund
when it had severe financial difficulties beginning March 1984. Eventually, the
main creditor of Pontiac foreclosed on Pontiac and sold its assets to Artistic
Furniture, an unrelated company, in August 1985. In connection with the
purchase, the buyer – Artistic Furniture – negotiated a new collective
bargaining agreement with the union including the obligation to contribute to
the multiemployer pension fund. However, the buyer did not specifically assume
liability for the delinquent pension fund contributions that were not paid by
the seller between March 1984 and August 1985. The pension fund sued both
parties for delinquent pension contributions. There was apparently no claim for
any withdrawal liability since the buyer bargained to continue in the pension
fund.

The Seventh Circuit cited Supreme Court in Golden
State Bottling Co. v. N.L.R.B.
,[15] in finding, that liability of asset purchaser for unfair
labor practice (unlawful discharge) under the NLRA could be imposed on the
successor who continued the predecessor’s operations and who had notice of the
pending unfair labor practice charge at the time of the transaction, even
though there was no continuity of ownership (and therefore no de facto merger
or mere continuation). This protects Congressional intent under the National
Labor Relations Act of avoidance of labor strife and fee exercise of the
employees’ rights under the NLRA, and are achieved at a relatively minimal cost
to the bona fide successor, with minimal economic cost because the buyer is
aware of the obligation. Similar conclusions have been reached for other labor
law obligations and employment discrimination laws. Artistic Furniture applied
the rationale of Golden State Bottling Co. to multiemployer
pension liability under ERISA.[16]

ERISA §515, which requires employers to honor their
obligations under the plan or the labor agreement to make the contributions to
the pension fund, should be imposed on successors as well since ERISA’s purpose
is to protect other employers in the fund and the PBGC (and presumably
employees if their benefits are affected), which applies when delinquent
contributions are made. However, this successor liability will only apply where
there was sufficient evidence of (i) continuity of operations, and (ii) prior
knowledge by the buyer of this liability.

The Seventh Circuit held that there was sufficient
evidence of continuity of operations since Artistic Furniture: (i)
employed substantially all the workforce, (ii) operated from the same location,
(iii) used predecessor’s machines, (iv) produced the same products, (v)
completed open work orders, (vi) honored the predecessor’s warranties, and
(vii) two of its officers remained with the successor. The owners, officers and
directors were all different (except for one CFO who stayed on). The court
stated that it did not matter that there was no continuity of ownership. The
case was remanded to district court, though, to determine if there was
sufficient knowledge of the liability.

Comment
on Artistic Furniture Case — Are ERISA Laws Like Unfair Labor Practices &
Employment Discrimination Laws?

The rationale for broadened successor liability for
labor law obligations and employment discrimination is that these statutes were
enacted to protect employees, and where there is continuity of operations,
employees should be able to expect to retain these protections from their
current employer. Artistic Furniture expands this rationale to
ERISA liability for delinquent contributions to multiemployer plans because
ERISA is intended, among other purposes, to protect other employers and the
PBGC. Query whether this is a good analogy—unfair labor practice rules and
nondiscrimination laws are intended to protect the employee vis-à-vis the
employer. But for multiemployer pension contributions the parties protected are
primarily other employers in the fund and the PBGC and they should be like any
other contractual obligation that is subject to the common law successor
liability rules. There are some benefits to employees also, by avoiding the
plan becoming bankrupt and employees losing a portion of their benefits, as
stated below.

A similar question is raised by Einhorn v. M.L.
Ruberton Const. Co.
,[17] which is one of the few cases to disagree with the Artistic
Furniture
 broadened successor liability, although this holding was
subsequently overturned by the Third Circuit in Einhorn v. M.L.
Ruberton Construction Co.
,[18] as noted below. The district court in the above case
disagreed with Artistic Furniture and held that ERISA
obligations are different than unfair labor practice or employment
discrimination laws because the unfair labor practice and nondiscrimination
rules are designed to protect the employees, while successor liability for
delinquent contributions or withdrawal liability to multiemployer funds is a
corporate debt to multiemployer fund and is not a law directly protecting the
employee. A counter-argument to Einhorn is that ERISA rules,
while enforcing the union’s pension fund, indirectly protect employees from
losing benefits if the multiemployer plan does not have enough assets to meet
its obligations, and the PBGC guarantees are not sufficient.[19]  In any event, the district court ruling was overturned
by the Third Circuit.

It Does Not Matter That a Collective Bargaining
Agreement Imposed the Obligation for the Contribution

Note that finding successor liability in the Artistic
Furniture
 could not have been based entirely on the fact that a
collective bargaining agreement required the contribution to the fund, because
under labor law successors are generally not bound to the specific provision of
the collective bargaining agreement—although they do have a duty to bargain in
good faith—unless the contract was specifically assumed or the successor is
found to be the alter-ego of the predecessor (see below).

Other
Seventh Circuit Cases Finding Expanded ERISA Successor Liability

Several other Seventh Circuit decisions have found
expanded successor liability in ERISA withdrawal liability cases. See,
e.g., Moriarty v. Svec,[20] holding that where the son of the owner took over
operations and had knowledge of liability, there was successor liability to the
multiemployer pension and welfare fund).[21]   Similarly, a 2014 Seventh Circuit case, Sullivan
v. Running Waters Irrigation, Inc.,
 held that where a son’s businesses
contained a substantial continuity of operations of the father’s irrigation
business, and the son had knowledge of the multiemployer pension obligations
there would be successor liability.[22]

A 2015 Seventh Circuit case, Tsareff v. ManWeb
Services, Inc.
, held that in an asset sale where the buyer had notice of
contingent withdrawal liability to the multiemployer pension plan, even though
the asset purchase agreement specifically excluded plan liability assumption,
and the notice was only contingent (no withdrawal had occurred), successor
liability could nevertheless apply to the purchaser, and therefore the court
denied summary judgment which the buyer had sought, and the court remanded the
case to the district court to determine if there was a continuity of
operations, which is the other prong for successor liability.[23]

A 2016 Seventh Circuit case, Board of Trustees
of Automobile Mechanics’ Local No. 
701 Union and Industry
Pension Fund v. Full Circle Group, Inc.
, held that multiemployer withdrawal
liability could be imposed on an asset purchaser even though the purchaser may
not have had knowledge about the possibility of withdrawal liability before
signing the purchase agreement because the purchaser certainly knew that the
company was unionized and would have almost certainly known that the company
was required to contribute to a union pension fund.[24]

A 2018 Seventh Circuit case, Indiana Electrical
Workers Pension Benefit Fund v. ManWeb Services, Inc.
, held that there
could be successor liability for ERISA withdrawal obligations n an asset buyer
with notice and substantial continuity of operation, even though it was a
“big buyer,” i.e., the seller’s business was only a small portion of
the purchaser’s operations.[25]

Expanded ERISA Successor Liability in Other Circuits

Ninth Circuit [S3]

Ninth Circuit cases (some of which predate and are
cited in Artistic Furniture) have extended successor liability
concerning ERISA pension and welfare obligations under collective bargaining
agreements where there is a successor with substantial continuity between the
old and new operations (even without continuity of ownership).[26]

A 2015 Ninth Circuit caseheld that an asset purchaser
of a floor covering business could have successor liability for the seller’s
withdrawal liability as long as there was continuity of operations and the
buyer had notice of potential liability. In addition, the court held that the
successor employer could continue to be liable despite the “building and construction
industry” exception of ERISA §4203(b)[27] since if there is a common-law successor liability the
business and construction industry employer will be viewed as if it had
continued and there will be no ERISA §4203(b) exception.[28]

A 2018 Ninth Circuit case, held that there was
successor liability on a private equity group that purchased a Hawaiian hotel
in an asset purchase for the seller’s multiemployer withdrawal liability to a
multiemployer pension plan because of constructive notice of the seller’s
pension liability.26

Second Circuit

In Stotter Division of Graduate Plastics Co.
Inc. v. District 65, UAW
,[29] the Second Circuit ruled that an asset purchaser could
be liable for the predecessor’s unpaid contributions to a multiemployer plan in
accordance with the bargaining unit contract, and it upheld an arbitrator’s
decision to that effect.[30]

Sixth Circuit [S3]

A 2008 district court decision in the Sixth
Circuit, Schilling v. Interim Healthcare of Upper Ohio Valley, Inc.,
applied broad successor liability in ERISA contexts such as multiemployer
withdrawal liability, like the Seventh Circuit Artistic Furniture case.[31] In addition, the Sixth Circuit 2018 case of PBGC
v. Findlay Industries, Inc
., et al.,[32] discussed below, has expanded successor liability even
to single-employer pension termination liability.

Third
Circuit –District Court case disagreed with Artistic Furniture but was
Overturned by the Third Circuit

A New Jersey 2009 district court casewas one of few
cases and perhaps the only federal case to specifically disagree with Artistic
Furniture
. The district court held that ERISA is different than labor law
unfair labor practice claims or employment discrimination laws because those
laws are designed with Congressional intent to directly benefit the employees,
while successor liability to a multiemployer fund for delinquent contributions
or withdrawal liability is a corporate debt to the multiemployer fund and is
not a law directly protecting the employee.[33]

However, the Third Circuit in a 2011 decisionoverturned
the district court decision and held that a purchaser could be held liable for
successor liability for the predecessor employer’s delinquent multiemployer pension
contributions because of continuity of operations (continuity of workforce,
management, equipment and location, completion of work orders begun by
predecessor, constancy of customers, and notice of the liability before the
sale) even without continuity of ownership.[34]

There are also other district course cases in the Third
Circuit cases providing for expanded successor liability.[35]

Other
Circuits

It is unclear whether any other circuits would disagree
with Artistic Furniture’s ERISA successor liability rule.

Why
Should Asset Sale Trigger Withdrawal Obligation if Buyer Has Successor
Liability?

Note that even though there may be successor liability
on the withdrawal liability or other liability to the fund, the asset sale
itself would appear to still be treated as a withdrawal under ERISA (unless an
ERISA §4204 contract is entered into). This result is puzzling: If the asset
sale is disregarded by having the buyer pick up liability as a successor, why
should a sale of assets be treated as a withdrawal under ERISA? It would appear
that by operation of law there is a withdrawal (and the parties may be bound to
the form they have chosen), and although equity dictates that there should be
recourse against successors this does not change the basic nature of the asset
sale.

SUCCESSOR LIABILITY IN OTHER
ERISA CONTEXTS

Successor
Liability for Single-Employer Plan Termination Liability

A 2018 Sixth Circuit case, PBGC v. Findlay
Industries, Inc
.,[36] has applied broad successor liability for
single-employer Title IV termination liability. In that case, Findlay
Industries folded in 2009 and its assets were indirectly sold to companies
owned by the son of the founder. The business in hands of the son’s companies
soon began to run the same plants, hiring many of the same employees, and
selling to the former company’s largest customer. The Sixth Circuit,
overturning the lower court, ruled that the expanded successor liability should
be applied to ERISA obligations, such as single-employer pension plan
termination liability under ERISA, since there was a continuation of the
business since this broadened successor liability services fundamental ERISA
policies. The Sixth Circuit did note that several circuits have broadened successor
liability in ERISA MPPAA withdrawal, for example, the Seventh Circuit and Ninth
Circuit cases cited above.[37]

Successor Liability for Retiree Health and Other
Welfare Obligations

Regard­ing successor liability for retiree health or
other welfare obligations in an asset sale, common-law successor liability
exceptions would apply (i.e., express or implied assumption, de facto merger,
mere continuation of seller or transfer for fraudulent purposes).

However, several cases have applied broadened successor
liability for retiree health or other ERISA welfare benefits where there is
continuity of operations and notice of liability (even if there is no continuity
in ownership), and ERISA’s broadened successor liability is not limited to
pension liability.[38]

Successor Liability for Top-Hat Supplemental Pension
Obligation

In Brend v. Sames Corp.,[39] the court applied the expanded ERISA successor liability
of Artistic Furniture to obligations under a top-hat executive
retirement plan since top-hat plans are generally subject to ERISA.[40] The court noted that while top-hat employees need less
protection than rank and file employees, ERISA nevertheless found it
appropriate to offer the protections of ERISA to all employees.

Whether
ERISA Fiduciary Obligations Have Expanded Successor Liability
 [S2]
[UC/LC]

Concerning ERISA fiduciary liability, a 2009 district
court case has held that ERISA fiduciary liability would not have broadened
successor liability.[41] However, another 2003 district court case stated in
dictum that ERISA fiduciary duties could have broadened ERISA successor
liability.[42] Where a buyer specifically assumes the ERISA obligation,
the buyer will have successor fiduciary liability.[43]

BROADENED SUCCESSOR
LIABILITY IN LABOR LAW AND EMPLOYMENT DISCRIMINATION CONTEXTS

As stated above, the Supreme Court in Golden
State Bottling Co. v. N.L.R.B.
, 414 U.S. 168 (1973), held that liability of
asset purchaser for unfair labor practice (unlawful discharge) under the NLRA
(where a union member was discharged for allegedly engaging in protected union
activities) could be imposed on successor who continues predecessor’s
operations and who had notice of the pending unfair labor practice charge at
the time of the transaction, even though there was no continuity of ownership
(and therefore no “de facto merger” or “mere
continuation”). This protects This protects Congressional intent under the
National Labor Relations Act of avoidance of labor strife and fee exercise of
the employees’ rights under the NLRA, and are achieved at a relatively minimal
cost to the bona fide successor, because buyer is aware of the obligation.
Similar conclusions have been reached for other labor law obligations and
employment discrimination laws.[44] 

Similarly, the courts have imposed broadened successor
liability in cases involving employment discrimination.[45]

The National Labor Relations Act of 1935, which deals
with the establishment of collective bargaining relationships, imposes an
obligation on an employer and union to bargain in good faith.[46]  When a corporation is taken over by a new employer
in an asset sale with substantial continuity of operations and workforce, there
is an obligation on the new employer to bargain in good faith with the existing
union representatives.[47]  However, unless the buyer specifically assumes the
contract or is found to be the alter-ego of the predecessor, the new employer
is not bound by the specific terms of the existing collective bargaining
agreement.[48]

OTHER ERISA ISSUES WITH ASSET
SALES

Emergence
from Bankruptcy Like an Asset Sale [S2] [UC/LC]

With regard to a stock sale or merger, the purchaser
should in the ordinary course step into the shoes of the seller for any
termination liability even if they resulted from termination of the plan when
it was with the seller.[49] However, where a purchaser in a stock sale or merger
acquires a bankrupt corporation with its pension plan, courts have held that
the purchaser would not have controlled group liability because the ownership
interests have been extinguished in the bankruptcy, and there would not be
successor liability.[50] In a case where successor liability would apply to an
asset purchaser, the purchaser from the bankruptcy could also have successor
liability.[51]

Alter-Ego
Theory as Applied to Asset Purchases
 [S2] [UC/LC]

As discussed above, on occasion courts have found a
shareholder liable for ERISA and other liabilities of the corporation under the
doctrine of piercing the corporate veil (alter ego), for example, where there
is fraud, disregard by the owner of the separate character of the corporation
or shareholders undercapitalize the corporation. Courts have sometimes used
alter ego theory to apply successor liability.[52]

ERISA §4069(b) and §4218 Successor Liability for Mere
Changes in Form [S2] [UC/LC]

To avoid controlled group liability, companies
sometimes attempt to remove themselves from the controlled group.
ERISA §§4069(b) and §4218 provide that for purposes of termination
liability and withdrawal liability, respectively, if an entity ceases to exist merely
because of a change in identity or form, a liquidation into the parent
corporation or a merger, consolidation or division, the successor will remain
liable for the liability. This provision would not, however, cover ordinary
asset sales. Successor liability in asset sales would be subject to the case
law discussed above.

ERISA §4069(a) Liability [S2]
[UC/LC]

To avoid controlled group liability, companies
sometimes attempt to remove themselves from the controlled group. Typically,
this takes the form of a company selling or spinning off a subsidiary or
division and transferring severely underfunded pension plans with those sold
subsidiaries or divisions. The PBGC has been successful in certain cases in
having a court declare such a transaction as a sham.[53] In addition, the PBGC was successful in having ERISA §4069
enacted in 1986 as part of SEPPAA.

ERISA §4069(a) provides that if a person enters into a
transaction with a principal purpose of evading liability under Title IV, the
PBGC can assert liability on such person as if it was still a member of the
controlled group for any plan termina­tion that results within five years of
the transaction.[54]

ERISA
§4212(c)

If a principal purpose of a transaction is to evade or
avoid liability, withdrawal liability is imposed as if the transaction had not
occurred (i.e., even if the entity left the controlled group in the
transaction).[55] Several cases have applied ERISA §4212(c) to impose
withdrawal liability. Other cases have held that ERISA §4212(c) did not apply
despite the avoidance of withdrawal liability. Courts have on occasion found
individuals liable under ERISA §4212(c) for participating in a scheme to evade
or avoid liability even though multiemployer withdrawal liability generally
only applies to the employer. ERISA §4212 does not have the five-year limit
that ERISA §4069 has (regarding attempt to evade termination liability).

Successor
liability
 [S2] [UC/LC]

In a corporate transaction, assuming there was no
intent to evade liability and ERISA §4069 and §4212(c) are not applicable, the
general successor liability rules should apply, i.e. the ordinary common law
exceptions to lack of successor liability and the broadened successor liability
rules for ERISA obligations under the Artistic Furniture line
of cases.

ASSET SALE AS WITHDRAWAL AND
ERISA §4204 AGREEMENTS

Asset
Sale as a Withdrawal

An asset sale will result in a withdrawal from the plan
by the seller. This may be advantageous to the buyer, as the buyer will not be
liable, absent some successor liability theory. For the seller, however, a
stock sale would be preferable, as there would be no automatic withdrawal from
the multiemployer plan. Another option is an ERISA §4204 contract discussed
below.

ERISA
§4204 Contracts to Avoid Multiemployer Liability in Asset Sales

As discussed above, where an asset sale occurs there
has by definition been a complete withdrawal by the target since it ceases to
exist, and even if the buyer continues to make required contribu­tions, members
of the controlled group of the target, e.g., the seller, could be liable for
with­drawal liability. There is a statutory exception, however, in ERISA §4204,
under which a complete or partial withdrawal will not occur solely because,[56] as a result of a bona fide arm’s-length sale of assets
to an unrelated party, the seller ceases covered operations or ceases to have
an obligation to contribute for such operations, provided that the following
are met: (i) the purchaser obligates to contribute a similar amount as the
seller (i.e., substantially the same number of base contribution units) (ERISA
§4204(a)(1)(A)); (ii) for a period of five plan years after the sale, the
purchaser posts a bond or escrow equal to one year of the Seller’s
contributions, i.e., the average annual contribution required based on the
greater of the previous three years or the annual contribution required over the
last year, and the bond or escrow will be paid to the plan if the purchaser
withdraws or fails to make contributions to the plan during the five year
period (ERISA §4204(a)(1)(B)); and (iii)the contract of sale must provide for
the seller to be secondarily liable if the buyer withdraws within a five-year
period and does not make payment (ERISA §4204(a)(1)(C)). Such an arrangement is
referred to as a ERISA §4204 contract.

If the purchaser withdraws before the end of the fifth
year after the sale and fails to make withdrawal liability payments, the seller
must pay the plan the amount that it would have been obligated to pay absent
the ERISA §4204 contract.[57] There may also be a seller bond/escrow requirement in
the following situation: if the seller sells substantially all of its assets or
liquidates within the five-plan year period after the sale, the seller must
post a bond or escrow for the amount that the seller would be liable absent the
ERISA §4204 contract.[58]

If the above requirements are met so that the seller
has no liability, the buyer inherits the five-year contribution history of the
seller.[59] An advantage to ERISA §4204 is that if the seller has a
long contribution history, taking the liability of only the last five years of
contributions can shed a company of a significant portion of potential
withdrawal liability.

The PBGC has the authority to waive the purchaser
bond/escrow requirement and contractual seller secondary liability requirement
of ERISA §§4204(a)(1)(B) and §4204(a)(1) (C). ERUnder this authority, PBGC
regulations enacted in 1984 contain a class variance of the bond or escrow requirement
and of the contractual requirement for the seller to be secondarily liable if a
buyer notifies the plan of its intention that the sale is to be covered by
ERISA §4204 and demonstrates to the satisfaction of the plan that one of the
following exceptions apply: (i) the bond or escrow would not exceed the lesser
of $250,000 or 2% of the average total annual contributions made by all
employers to the plan for the three most recent plan years; (ii) the
purchaser’s average net income after taxes for the most recent three years
equals or exceeds 150% of the amount of bond or escrow required; or (iii) the
purchaser’s net tangible assets as defined in PBGC Reg. §4204.2 equal or exceed
the otherwise allocable share of unfunded vested benefits. PBGC Reg. §4204.11-4204.13.
The request for a variance must contain financial or other information
sufficient to establish that one of these exceptions are met, and pending the
plan’s decision as to whether the variance is met, the purchaser cannot be
required to post the bond or escrow. PBGC Reg. §§4204.11(b), PBGC Reg.
§4204.11(c),  PBGC Reg. §4204.11(d). An individual exemption is also
available pursuant to ERISA §4204(c) under PBGC Reg. §§4204.21 and §4204.22.

  ERISA §4204 and PBGC Reg. §4204 do not
specifically state that seller and purchaser are each determined on a
controlled group basis, but based on ERISA rules generally, seller and
purchaser should be interpreted as each being determined on a controlled group
basis. 

Where there is no ERISA §4204 contract, purchasers of
assets are generally not held liable. However, see generally above regarding
successor liability for pension obligations. Also, the Seventh Circuit has held
that even where there is no §4204 contract the purchaser of assets may be
liable under the provisions of a particular collective bargaining agreement for
withdrawal liability.[60]

CONCLUSION

Successor liability in ERISA contexts—such as multi­employer
withdrawal liability—would, according to case law, be applicable if there is a
continuity of operations and notice to the buyer even if there is no continuity
of ownership. This expanded successor liability has been applied by courts not
just to withdrawal liability, but also to other ERISA contexts, such as
single-employer plan termination liability, top-hat plan, retiree health and
welfare plan obligations. In addition, case law has applied broad successor
liability for labor law obligations to bargain in good faith and employment
discrimination claims. Care must be taken by buyers in asset acquisitions to
account for possible broadened successor liability.


* Charles C. Shulman, Esq., Teaneck, NJ.  If you
have any questions or comments, feel free to contact Charlie at
cshulman@ebeclaw.com or 201-357-0577.

[1]    See, e.g., Dayton
v. Peck, Stow and Wilcox Co.
 (Pexto), 739 F.2d 690, 692 (1st
Cir. 1984) (successor not liable in product liability action since the purchase
of assets did not meet any of the four exceptions to the general rule); Murray
v. Miner
, 74 F.3d 402 (2d Cir. 1996) (based on New York law, shareholders
of successor corporation not liable for breach of employment contracts where
there was no employer-employee relationship between employees and successor at
the time of alleged wrong); Berg Chilling Systems, Inc. v. Hull Corp.,
435 F.3d 455 (3d Cir. 2006) (buyer of manufacturer’s assets had no successor
liability). See generally 15 Fletcher Cyclopedia of the Law of
Private Corporations, §7122, §7124, §7124.10, §7124.20, §7124.50, and
  §7125.

The successor liability rules are generally applicable
whether the successor is a corporation or another entity. Graham v.
James
, 144 F.3d 229, 240 (2d Cir. 1998) (traditional rule of corporate
successor liability and the exceptions to the rule are generally applied
regardless of whether the predecessor or successor organization was a
corporation or some other form of business organization; citing 63 Am. Jur. 2d
Products Liability §117 (1984)).

[2]    See,
e.g.,
 Florom v. Elliott Mfg., 867 F.2d 570 (10th Cir. 1989)
(conduct of successor corporation shows that it specifically assumed the
liability); Hudson Riverkeeper Fund, Inc. v. Atlantic Richfield Co.,
138 F. Supp. 2d 482 (S.D. N.Y. 2001) (corporation that expressly assumed
alleged polluter’s liabilities could be liable under Resource Conservation and
Recovery Act even though its subsidiary was current site owner).

[3]    See,
e.g.,
 Philadelphia Elec. Co. v. Hercules, Inc., 762 F.2d 303
(3d Cir. 1985), cert. denied 474 U.S. 980, 106 S.Ct. 384 (implied assumption of
liability where language of assumption agreement is broad); Harbison v.
Garden Valley Outfitters, Inc.,
 69 Wash. App. 590 (1993) (implied
assumption of liability where acquiring company agrees to assume seller’s
obligations to its customers).

[4]   See,
e.g.,
 Philadelphia Electric Co. v. Hercules, Inc., 762 F.2d
303, 310 (3d Cir. 1985), cert. denied 474 U.S. 980 (successor
liable for predecessor’s negligence as express assumption of liability as well
as de facto merger, where: (i) the purchaser exchanged its stock as
consideration for the seller’s assets so that the shareholders of the seller
corporation become a part of the purchaser corporation, (ii) predecessor’s
management and personnel became part of successor, (iii) predecessor was
required to transfer right to use its corporate name, and (iv) successor
continued to operate predecessor’s plants and produced same products as
predecessor); U.S. v. General Battery Corp., Inc., 423 F.3d 294 (3d
Cir. 2005) (acquisition of privately-held battery manufacturer part for
cash and part for stock constituted a de facto merger so that purchaser and its
successor would be responsible under the Comprehensive Environmental Response,
Compensation and Liability Act —Superfund law —for liability of battery
manufacturer);  U.S. v. Sterling  Centrecorp Inc., 960
F. Supp. 2d 1025 (E.D. Cal. 2013) (U.S. Environmental Protection Agency and
Calif. Dept. of Toxic Substances Control brought action against successor
corporation for liability of predecessors who operated gold mine causing
arsenic releases; district court held that the successor expressly and
impliedly assumed predecessor corporation’s liabilities relating to the arsenic
release, and in addition, the acquisition by the successor was a de facto
merger 
since there was continuity of
business enterprise and continuity of shareholders, seller ceased its
operations right after the sale and purchaser took over the operations upon the
asset acquisition); Lehman Brothers. Holdings, Inc. v. Gateway Funding
Diversified Mortgage. Services, L.P
., 785 F.3d 96 (3d Cir. 2015)
 (court
denied a summary judgement dismissal of action by purchaser of home mortgage
loans action against seller’s successor in interest under de facto merger
theory; there was a continuity of enterprise with same personnel and business
operations in the same location, some continuity of ownership with seller’s
shareholders retaining an ownership interest in the successor by reason of
contractual profit sharing entitlements, possibly cessation of business by the
seller company and there was assumption of ordinary business liabilities by the
purchaser).See in contrast, New York v. National Service
Industries, Inc.
, 460 F.3d 201 (2d Cir. 2006) (company that bought assets
of dry cleaning business was not liable for actions of seller under de facto
merger theory because there was no continuity of ownership; some evidence of
continuity of ownership is necessary to find a de facto merger).

[5]    E.g., Arnold
Graphics Industries, Inc. v. Independent Agent Center, Inc.
, 775 F.2d 38,
42 (2d Cir. 1985) (to find that a de facto merger has occurred there must be
continuity of shareholders); Louisiana-Pacific Corp. v. Asarco, Inc.,
909 F.2d 1260 (9th Cir. 1990) (there was no continuity of shareholders, which
is a prerequisite for finding de facto merger); New York v. National
Service Industries, Inc.
, 460 F.3d 201 (2d Cir. 2006) (cited above; some
evidence of continuity of ownership is necessary to find a de facto merger).
Some cases, however, have held that no one of these factors is either necessary
or sufficient to establish a de facto merger. Bud Antle, Inc. v.
Eastern Foods, Inc.
, 758 F.2d 1451, 1457-8 (11th Cir. 1985), reh’g
denied
 765 F.2d 154 (11th Cir. 1985) (successor not liable; based on
totality of circumstances the court did not find a de facto merger).

[6]   See,
e.g.,
 Medicine Shoppe Intern., Inc. v. S.B.S. Pill Dr., Inc.,
336 F.3d 801 (8th Cir. 2003) (pharmacy was successor of franchisee; for “mere
continuation,” factors include: (i) common identity of officers, directors and
stockholders; (ii) incorporators of successor also incorporated predecessor;
(iii) business operations are identical; (iv) transferee uses same trucks,
equipment, labor force, supervisors and name of the transferor; and (v) notice
has been given of the transfer to employees or customers). Other cases
formulate the factors as stated in the text.

See in contrast, Grand Laboratories, Inc.
v. Midcon Labs of Iowa,
 32 F.3d 1277 (8th Cir. 1994) (successor
corporation that purchased predecessor’s assets was not “mere continuation” of
predecessor under Iowa law where companies had no common shareholders or
directors; in determining whether one corporation is a continu­ation of
another, the test is whether there is a continuation of the corporate entity of
the transferor, not whether there is a continuation of the transferor’s business
operation); Mickowski v. Visi-Trak Worldwide, LLC, 415 F.3d
501 (6th Cir. 2005) (a corporation is not a “mere continuation” of the
corporation whose assets it has purchased for purposes of successor liability
just because it continues to provide the same services (continuation of
business operation), but rather the key element in the mere continuation theory
is the continuation of the corporate entity such as when one corporation sells
its assets to another corporation with the same people owning both corporations
— common identity of stockholders, directors, and stock).

[7]    See,
e.g.,
 Dayton v. Peck, Stow and Wilcox Co. (Pexto), 739
F.2d 690, 693 (1st Cir. 1984) (purchase of manufacturing company’s assets for
cash did not constitute a “de facto merger” or “mere continuation”; key element
of continuation is common identity of the officers, directors and stockholders
in the selling and purchasing corporations).

[8]    See,
e.g., Berg Chilling Systems, Inc. v. Hull Corp.
, 435 F.3d 455 (3d Cir.
2006) (where one company sells all of its assets to another company, the buyer
is not normally liable for the liabilities of the seller, though if circum­stances
indicate that there was a “de facto merger” of the corporations or that the
purchasing company was a “mere continuation” of the selling company, liability
would attach to buyer; the de facto merger test is similar to the mere
continuation test, except that the mere continuation test focuses on situations
in which the buyer is merely a restructured or reorganized form of the seller).

[9]    See,
e.g.,
 Lumbard v. Maglia, Inc., 621 F. Supp. 1529 (S.D. N.Y.
1985) (creditor of liquidated manufacturer adequately alleged successor
liability charging that various defendants had fraudulently created new entity
to carry on manufacturer’s business while avoiding its debts); Raytech
Corp. v. White
, 54 F.3d 187, 192 (3d Cir. 1995) (transferee corporation
could be liable for transferor corporation’s liabilities for asbestos exposure
even though transferor’s asbestos-related assets were not part of transaction;
issue was whether transfer was fraudulent attempt to avoid liability); U.S.
ex rel. Bunk v. Gov’t Logistics N.V
., 842 F.3d 261 (4th Cir. 2016)
(successor corporation could be liable for claims against the predecessor
corporation’s under False Claims Act for bid-rigging and plaintiffs had offered
sufficient evidence under a fraudulent transaction theory to survive summary
judgment).

[10]  Ray
v. Alad Corp.
, 560 P.2d 3, 19 Cal.3d 22 (Cal. 1977) (non-bankruptcy asset
sale; successor that continues to market a product line purchased from
predecessor assumes predecessor’s liability for defective products); Lefever
v. K.P. Hovnanian Enterprises, Inc.
, 734 A.2d 290, 292 (N.J. 1999) (asset
sale in bankruptcy case; acquiring a substan­tial part of manufacturer’s assets
and continuing to market good in same product line exposes purchaser to
successor liability).

[11] 
All section references herein are to the Internal Revenue Code of 1986, as
amended (the “Code”), or the Treasury regulations promulgated
thereunder, unless otherwise indicated.

[12] 
The liability of a transferee that may be enforced under I.R.C.§6901 may be
either at law or in equity. Regardless of whether enforcement is sought at law
or in equity, there are two fundamental elements to transferee liability: (1)
there must be a transfer of the taxpayer’s property to a third-party
transferee, and (2) the taxpayer must be liable for the tax at the time of
transfer and at the time transferee liability is asserted. Note that I.R.C.
§6901 does not impose successor liability, but rather allows a collection
mechanism where there is common law principles of successor liability. The
Supreme Court has ruled that transferee liability is predicated on state, not
Federal, law. C.I.R. v. Stern, 357 U.S. 39, 45 (1958). In general,
the elements of transferee liability in equity in a given state are those found
in that state’s fraudulent conveyance provisions.

[13]  See,
e.g.,
 In Matter of Motors Liquidation Company, 829 F. 3d 135
(2d. Cir. 2016) (in 2009 General Motors (Old GM) in a Chapter 11 bankruptcy
sold the bulk of its assets to a new entity (New GM) free and clear of
liabilities against New GM; Second Circuit held that free and clear provisions
could not be enforced to negate all of the ignition switch defect claims
because some of the claimants had not received adequate notice of the sale
order).

[14] 
920 F.2d 1323 (7th Cir. 1990). Artistic Furniture in citing a
1987 Title VII case, notes as a factor “whether the predecessor is able, or was
able prior to the purchase, to provide the relief requested.” However, it does
not consider this factor in discussing the successor liability for Artistic
Furniture. The Artistic Furniture case does not emphasis on
this provision. Most of the other cases regarding broadened successor liability
do not mention this factor. Also, as noted in Chicago Truck Drivers, Helpers
and Warehouse Workers Union (Independent) Pension Fund v. Tasemkin, Inc.
,
59 F.3d 48 (7th Cir. 1995), availability of relief from predecessor was not
dispositive in successor liability case, but rather was factor to be considered
along with other facts in particular case.

[15] 414
U.S. 168 (1973).

[16] Pub.
L. No.
93-406.                            

[17] 665
F. Supp. 2d 463 (D.N.J. 2009).

[18] 632
F.3d 89 (3d Cir. 2011).

[19] 
The single-employer plan limit is $64,432 a year in 2017. However, the PBGC
generally guarantees a much smaller amount for multiemployer pension plan
benefits, depending on the type of benefit, the dollar amount of the benefit,
and the date on which the benefit provision was adopted.

[20] 164
F.3d 323 (7th Cir. 1998).

[21]  Moriarty
v. Svec
, 164 F.3d 323 (7th Cir. 1998) (expanded ERISA successor liability;
son who took over funeral home business from father was liable for unpaid
contributions to multiemployer pension and welfare fund because there was
continuity of operations and knowledge of liability).

[22]  Sullivan
v. Running Waters Irrigation, Inc.
, 739 F.3d 354 (7th Cir. 2014) (where a
company went out of business and the son who managed that business set up two
other businesses which bought equipment from the first company and bought
equipment from the first company, there would be successor liability for
multiemployer withdrawal liability since the successors had notice of the claim
before the acquisition and there was a substantial continuity of operation of
the business).

[23]  Tsareff
v. ManWeb Services, Inc.
, 794 F.3d 841 (7th Cir. 2015) (in sale of assets
by a unionized electrical contractor (Tiernan & Hoover) to a non-union
engineering company (ManWeb), multiemployer pension plan brought suit against
the successor, ManWeb; court held that notice of “contingent” liability to the
multiemployer plan was sufficient to be considered notice even though no
withdrawal has occurred; court denied summary judgment for the successor
company; court remanded to the district court to address the successor liability
continuity of operations requirement, which was not addressed previously by the
district court; the Seventh Circuit did not address the district court’s
holding that ManWeb’s continuation of work previously done by Tiernan &
Hoover should nevertheless not be imputed to Tiernan & Hoover in
determining whether Tiernan & Hoover had a complete withdrawal under the
Building and Construction Industry exception of ERISA §4203(b)).

[24]  Board
of Trustees of Automobile Mechanics’ Local No. 
701 Union and
Industry Pension Fund v. Full Circle Group, Inc.
, 826 F.3d 994 (7th Cir.
June 24, 2016) (multiemployer pension fund sued asset purchaser, Full Circle
Group (FCG), for withdrawal liability incurred by the target company, Hannah
Maritime Corporation (HMC), when HMC became insolvent; no plan liabilities were
transferred to the buyer; the buyer’s owner (who was the son of the seller’s
owner) knew before signing the purchase agreement that HMC was unionized and
therefore almost certainly knew that the company would be required to
contribute to a union pension fund, which should have alerted buyer to the
possibility of withdrawal liability; ERISA successor liability may be imposed
if there is substantial continuity in the operation of the business before and
after the sale and the asset buyer had notice of the withdrawal liability; the
court held that enough evidence was presented of continuity of operations to
preclude summary judgment in favor of the buyer on grounds of discontinuity,
and enough evidence that buyer had notice of the seller’s pension fund
liability to preclude summary judgment on the ground that buyer lacked notice
of possible successor liability; therefore, the district court’s summary
judgment for the buyer was overturned, and the case was remanded to the
district court for a trial).

[25]  Indiana
Electrical Workers Pension Benefit Fund v. ManWeb Services, Inc
., 884 F.3d
770 (7th Cir. 2018) (multiemployer pension ERISA withdrawal liability could
apply to the asset purchaser; in determining whether there was continuity of
operations between asset purchaser and seller the district court improperly
focused on dilution of employer’s operations in those of larger putative
successor; continuity of intangible assets, workforce, business services and
customers all weighed in favor of finding successor liability).

[26]  See,
e.g.,
 Hawaii Carpenters Trust Funds v. Waiola Carpenter Shop, Inc.,
823 F.2d 289 (9th Cir. 1987) (in employee buyout of company there was
substantial continuity between the enterprises (looking at factors such as
whether there is the same basic operation, the same plant, the same workforce,
the same supervisors, the same machinery and the same product), and as a
successor employer the successor was requested to abide by the terms and
conditions of the predecessor’s collective bargaining agreement unless it has
timely bargained to an impasse; in addition, there was an assumption of the
collective bargaining agreement; successor is liable for delinquent
contributions to health and pension trust funds under collective bargaining
agreement; also held with regard to delinquent contributions to a pension plan
that the six-year statute of limitations under ERISA should be used); Trustees
for Alaska Laborers-Construction Industry Health and Sec. Fund v. Ferrell
,
812 F.2d 512 (9th Cir. 1987) (member of a joint venture who continued to
operate business with same employees and equipment after joint venture ceased
operations was a successor employer for purposes of multiemployer withdrawal
liability; company is deemed a successor if it hires most of its employees from
the predecessor employer’s workforce and if it conducts essentially the same
business as the predecessor); Board of Trustees of Northwest
Ironworkers Health & Sec. Fund v. Tanksley
, NO. CV-07-367-RHW., 2010 BL
37579 (E.D. Wash. 2010) (company taken over in bankruptcy was successor
employer since operated out of same premises, performed same type of work and
used similar assets, and the same officers and partners served on both
entities, and is obligated to collective bargaining agreement as alter ego).

[27] ERISA
§4203(b) provides that a building and construction industry employer (e.g., a
contractor) that ceases to contribute and the employer does not continue to
perform that type of work in that jurisdiction of the collective bargaining
agreement within five years will not incur withdrawal liability.

[28] Resilient
Floor Covering Pension Trust Fund v. Michael’s Floor Covering
, 801 F.3d
1079 (9th Cir. 2015)  (Studer’s Floor Coverings went out of business and
some of its assets were sold to Michael’s Floor Covering who continued the
business at the same store; Studer’s contributed to Resilient Floor Covering
Pension Trust for its union employees, but that ceased when Studer’s closed;
Michael’s operated at same store front with some of same machines and some of
the same workers, and with many of the same clients as Studer’s; court held
there could be successor liability as long as there is continuity of operations
and notice of the potential liability; the construction industry exception of
ERISA §4203(b) provides that for a business and construction industry employer
there will be withdrawal liability only if the employer continues to perform
the same type of work in the jurisdiction of the union or resumes such work
within five years; broadened successor liability should apply to withdrawal
liability just like previous cases have held for delinquent pension
obligations; for the construction and industry exception if there is a
successor there is a continuation of work and the exception should not apply;
court in footnote noted that no circuit court has held contrary to Artistic
Furniture
; court stated that this is the first time a circuit court rules
regarding withdrawal liability successor liability; contrary to the district
court, the Ninth Circuit gave greater weight to the successor taking over the
predecessor’s customer base and less emphasis on continuity of workforce; court
remanded for determination of successorship factors).

          See on
rem’d
, Resilient Floor Covering Pension Trust Fund
v. Michael’s Floor Covering, Inc.
, No. 11-cv-05200-JSC, 2016 BL 321052(N.D.
Ca. Sept. 28, 2016) (on remand, finding for successor defendant even after
Third Circuit reversal because no notice of liability actually existed, even
though Michael’s Floor Covering owner knew there was a union since that is
insufficient to support a reasonable inference if successor’s knowledge since
successor had no knowledge that the business was potentially liable for closing
down the business and withholding from the pension fund even though it may have
known the business contributed to a pension fund; court distinguished Full
Circle Group
 2016 Seventh Circuit case, discussed below, where lack of
familiarity with the concept of withdrawal liability could not be an excuse
since the buyer was aware of the pension fund and he had legal counsel who must
have known that most pension funds are underfunded, while in Michael’s Floor
Covering there was no evidence Michael’s knew of the union pension fund and he
had no counsel).

26 
Heavenly Hana LLC v. Hotel Union & Hotel Industry of Hawaii Pension Plan
, 891
F.3d 839 (9th Cir. 2018) (a 2018 Ninth Circuit case held that there would be
successor liability on a private equity group, Heavenly Hana LLC, which
purchased the Ohana Hotel in Maui, Hawaii from Ohana Hotel Company, LLC for the
seller’s multiemployer withdrawal liability when the seller formally withdrew
from a multiemployer pension plan; there was a substantial continuity of
operations of the hotel; although the seller was not given specific notice of
the withdrawal liability and the attorneys advised (incorrectly) that absent an
express assumption of liability the buyer would not assume the withdrawal
liability, there was constructive notice because buyer had previously operated
a hotel that was part of that multiemployer plan, in previous acquisitions that
private equity group had instructed its agents to review any potential
withdrawal liability, the asset purchase agreement indicated that the seller
had contributed to a multiemployer pension plan and the plan’s annual funding
notice showing its underfunding was publicly available on the internet).

[29] 991
F.2d 997 (2d Cir. 1993).

[30] 
In Stotter, a manufacturer had obligations to a multiemployer
pension plan which it had ceased to make and the union commenced arbitration
pursuant to the collective bargaining agreement. In the meantime, the company
had defaulted on loans and the bank foreclosed on the assets. The successor
continued with the same employees at the same location. The arbitrator ruled
that because the buyer was a successor employer to the seller, it had a duty to
participate in the arbitration and it was jointly and severally liable for any
delinquent contributions. (An arbi­trator’s award is generally upheld if
arguably construing the contract and acting within the scope of its authority.)
There was an adequate basis for its decision to hold the purchaser liable for
the delinquent contributions in light of Artistic Furniture and other cases.

See, however, Board of Trustees of Sheet Metal Workers
Local Union No. 137 Insurance, Annuity and Apprenticeship Training Funds v.
Silverstein, No. 92 Civ. 8519 (S.D. N.Y. 1995), where the court held that
liability for unpaid contributions to the Insurance, Welfare, Annuity and
Apprenticeship Funds could not be imposed on an asset purchaser even under the
Stotter and Artistic Furniture rationale, because there was not a sufficient
continuity of identity, where there was no real continuity of workforce and the
businesses were not identical.

[31]  See,
e.g.,
 Schilling v. Interim Healthcare of Upper Ohio Valley, Inc.,
44 E.B.C. 1988, (unpublished) (S.D. Ohio 2008; which is in the 6th Circuit)
(also quoting two other district cases in the Sixth Circuit; court found that
under standards of the Seventh Circuit case of Upholsterer’s Int’l
Union v. Artistic Furniture
 there would be successor liability for
ERISA and therefore the successor in Schilling was liable for the unpaid
medical claims under the ERISA health plan; court looked to Artistic Furniture
test whether buyer had no prior knowledge of the claim and whether there is
continuity at the business operations).

[32] 902
F.3d 597 (6th Cir. 2018).

[33]  Einhorn
v. M.L. Ruberton Construction Co
., 665 F. Supp. 2d 463 (D.N.J. 2009) (Statewide
Hi-Way Safety, which employed union workers, sold its assets to M.L. Ruberton
Construction Co, a non-union company, for $1.6 million; seller had been
obligated to make contributions to three multiemployer pension plans under
ERISA; Ruberton agreed to take union employees but did not assume the $500,000
outstanding obligation to the Philadelphia Teamsters Pension Trust and Welfare
Trust; district court stated that even with continuity of operations and
notice, there was no continuity of ownership; court found that absent a general
common-law finding of successor liability under the four exceptions above,
there is no special ERISA successor liability; this is in contrast to unfair
labor practices and employment discrimination where unfairly treated workers or
victims of discrimination may have no other practical recourse than to their
current employer, but ERISA plans can collect delinquent contributions from
seller or from proceeds of sale under constructive trust theory; thus, an ERISA
fund does not need the same protections as an individual employee, contrary to
Artistic Furniture; summary judgment for the buyer was granted).

The district court in Einhorn brought
support from a Third Circuit case that indicated that ERISA liability would be
imposed after a merger—but not necessarily after an asset sale—because the
Supreme Court Case of Golden State Bottling Co. applies broadened
successor liability only to unfair labor practices but not to corporate debt
such as pension obligation to union. Teamsters Pension Trust Fund of
Philadelphia & Vicinity v. Littlejohn
, 155 F.3d 206, 209 (3d Cir. 1998)
(court notes that parties argue over application of cases re development of
corporate successorship in federal labor law, such as Golden State Bottling Co.
where the Supreme Court held that successor liability is broader when the
obligation involved is a collective bargaining agreement than when an ordinary
debt is involved; in other cases Supreme Court has also stated that employer
may be bound by collective bargaining agreement of predecessor as long as it
had notice of obligation and continued operations of predecessor even if only
assets sold and not a merger; Third Circuit states that those cases are
somewhat distinguishable because they dealt with the application of labor law
concepts and the terms of a collective bargaining agreement, but in this case
only the transfer of a valid and ordinary debt is at issue which just happens
to have its genesis in the terms of a collective bargaining agreement).

The counter-argument to the Einhorn district
court ruling is that ERISA rules, while enforcing the union’s pension fund,
also may lead to loss of benefits by employees if the multiemployer fund does
not have enough assets to meet its obligations and the PBGC guarantees are
limited (single employer limit is $60,136 a year in 2016). Also, as the Third
Circuit in overturning the district court case, at Einhorn v. M.L.
Ruberton Construction Co.
, 632 F.3d 89 (3d Cir. 2011), noted, absent an
imposition of successor liability, the other employers will be forced to make
up the difference to ensure that workers receive their entitled benefits.

[34]  Einhorn
v. M.L. Ruberton Construction Co.
, 632 F.3d 89 (3d Cir. 2011) (the assets
of Statewide Hi-Way Safety were sold to M.L. Ruberton Construction Company (a
non-union company), and there was continuity of operations and the buyer had
notice of the obligations to the Philadelphia Teamsters pension fund; the Third
Circuit agreed with the Seventh Circuit Artistic Furniture case that labor law
successor rules should be extended to ERISA obligations since failure to pay contributions
can harm plan participants; thus the purchaser of assets would be liable for
seller’s delinquent ERISA fund contributions when the buyer had notice of the
liability prior to the sale and there was a continuity of operations; the case
was remanded to the district court for further proceedings).

[35] See,
e.g.,
 Central Pennsylvania Teamsters Pension Fund v. Beer
Distributing Company
E.B.C. 1037 (unpublished; E.D. Pa. 2009) (the asset
purchaser was liable as successor for ERISA withdrawal liability; court noted
that Federal courts have expanded successor liability for ERISA; successor and
predecessors are related entities through family ownership, successor assumed
customers, took over facility, rehired nearly all employees, and there may have
been an implied assumption of liability; case on its face supports Artistic
Furniture
, and contradicts the M.L. Ruberton district
court case, though it can be distinguished in that in this case all the factors
could, in any event, lead to a general common law exception such as a de facto
merger). See also Teamsters Local 469 Pension Fund v. J.H.
Reid General Contractors
, 2020 E.B.C. 401, 387 (D. N.J. 2020) (district
court denied summary judgement for the Pension Fund because a number of issues
remained to be clarified, including (i) whether one of the defendants (Reid
Recycling) was in the same controlled group as the employer that withdrew from
the Pension Fund (Reid General Contractors) at the time of such withdrawal, and
(ii) whether the buyer of Reid Recycling in a transaction that occurred after
the Pension Fund withdrawal could be liable under expanded successor liability
in accordance with the principles set forth in the M.L. Ruberton
Construction Co.
 Third Circuit decision).

[36]   902
F.3d 597 (6th Cir. 2018).

[37] Findlay
Industries, Inc., et al
., 902 F.3d 597 (case deals with two issues relating
to the Findlay Industries pension plan formed in 1964; first, in 1986 Findlay
transferred ownership of the properties on which the plants were operating to a
trust for the benefit of the family of the owner of the company, and the
properties were leased back by the family trust to the company; the Sixth
Circuit, overturning the district court, held that the family trust that leased
properties to the company were engaged in a trade or business and could be
liable for controlled group liability for any pension plan underfunding;
second, in 2009 after Findlay Industries folded the company was indirectly sold
to companies owned by the son of the founder, and the business in hands of the
son’s companies soon began running the same plants, hiring many of the same
employees, and selling to the former company’s largest customer; the Sixth
Circuit, overturning the district court, ruled that expanded successor
liability should be applied to the Findlay pension plan’s termination liability
under ERISA as this broadened successor liability services fundamental ERISA
policies, and there was a continuation of operation).

[38]  See,
e.g.,
 Schilling v. Interim Healthcare of Upper Ohio Valley, Inc.,
44 E.B.C. 1988, (S.D. Ohio 2008) (court found that under standards of the
Seventh Circuit case of Artistic Furniture there would be
successor liability for ERISA plans where there was continuity of business
operations and prior notice of the claim, and therefore the successor was
liable for the unpaid medical claims under the ERISA single-employer health
plan); Moriarty v. Svec, 164 F.3d 323 (7th Cir. 1998)
(broadened successor liability under Artistic Furniture applies
to unpaid contributions to multiemployer pension and welfare funds); Bender v.
Newell Window Furnishings, Inc., 681 F. 3d 253 (6th Cir. 2012) (upheld
district court decision that the successor employer, Newell Window, was liable
for retiree health benefits provided for under the collective bargaining
agreement of its predecessor because there was an express assumption of
liability by Newell Window of the prior collective bargaining agreement, and in
addition “there seems to be no question that there was also a substantial
continuation of operations at the plant by Newell Windows and its
predecessors”); Hawaii Carpenters Trust Funds v. Waiola Carpenter Shop,
Inc.
, 823 F.2d 289 (9th Cir. 1987) (court held that since there was
continuity of operations (looking at factors such as whether: (i) there has
been a substantial continuity of the same business operations, (ii) the new
employer uses the same plant, (iii) the same or substantially the same
work-force is employed, (iv) the same jobs exist under the same working
conditions, (v) the same supervisors are employed, (vi) the same machinery,
equipment, and methods of production are used, and (vii) and the same product
is manufactured or the same service is offered), and in addition there was
assumption of the collective bargaining agreement, the successor is liable for
various multiemployer health and welfare fund obligations based on the
collective bargaining agreement entered into with the predecessor). See
also
 Grimm v. Healthmont, Inc., 8 Wage & Hour Cas. 2d (BNA)
504, 2002 WL 31549095 (D. Or. 2002) (court cited cases involving ERISA pension
claims that buyer of assets liable for previous employer’s obligations under an
ERISA plan if there is continuity of operations and notice of potential
liability; court applied these broadened successor liability cases to facts in
this case, which involved severance plan (which was an ERISA welfare plan)).

See, in contrast, Board
of Trustees of Sheet Metal Workers Local Union No. 137 Insurance, Annuity and
Apprenticeship Training Funds v. Silverstein
, No. 92 Civ. 8519 (S.D. N.Y.
1995) (unpublished) (liability for unpaid contributions to the Insurance,
Welfare, Annuity and Apprenticeship Funds could not be imposed on an asset
purchaser even under the Stotter and Artistic
Furniture
 rationale, because there was not a sufficient continuity of
identity, as there was no real continuity of workforce (neither the majority of
the seller’s employees nor the majority of the buyer’s employees were involved)
and the businesses were not the same (both involved construction of signs but
the specific nature of the business was different)).

Where the retiree health obligation is provided for in
a collective bargaining agreement and an asset buyer assumes the collective
bargaining agreement the buyer would be obligated with regard to the retiree
health. See, e.g., Bish v. Aquarion Services Co., 289
F. Supp. 2d 134 (D. Conn. 2003) (buyer of assets agreed to assume collective
bargaining agreement which contained retiree health obligations; court held
that buyer would continue to be obligated for the retiree health obligation
under the LMRA and ERISA; court noted that ERISA recognizes such liability on
the successor, for example, regarding ERISA §409 fiduciary liability where
case-law provides that nothing precludes a later fiduciary from assuming by
contract the ERISA obligations of a former fiduciary, and case-law has also
held that where a successor assumed the obligation in the collective bargaining
agreement to contribute to a multiemployer plan the successor would be liable
under the LMRA and ERISA; therefore court denied motion to dismiss claims). See
similarly, cases cited in the beginning of the footnote.

See also Williams v. Wellman
Thermal Systems Corp.
, 684 F. Supp. 584 (S.D. Ind. 1988) (a buyer who
assumes retiree health liability cannot create in the purchase agreement a
right to amend or terminate the plan that did not otherwise exist under the
plan itself).

[39] 28
E.B.C. 2905 (N.D. Ill. 2002).

[40]  Brend
v. Sames Corp.
 found that an asset buyer may have successor liability
for a top-hat executive retirement contract even though specifically excluded
in the asset purchase agreement, since as an ERISA plan it was subject to the
continuity of operations and notice standards under Artistic Furniture for
successor liability, even though there is no continuity of ownership. In this
case there was notice of the liability and a genuine issue of material fact
whether there was substantial continuity.

See Feinberg v. RM Acquisition, LLC, 629
F.3d 671 (7th Cir. 2011) (asset buyer was not obligated under top-hat plan
because there was no continuity of operations).

[41]  In
re
 Washington Mutual, Inc. Securities, Derivative & ERISA
Litigation
, BL 219740, 47 EBC 2505(W.D. Wash. 2009) (whether a company can
be liable based upon an expanded ERISA inherited liability for breach of ERISA
fiduciary duties is a question of first impression, and the court believes that
broad successor liability should not apply in this case, stating that “while
compelling in the context of issues like plan contributions, there is no reason
to think the test encompasses the myriad of concerns present in the context of
liability based on the duties of prudence and loyalty”).

[42]  Bish
v. Aquarion Services Co.
, 289 F. Supp. 2d 134 (D. Conn. 2003) (as discussed
above, Bish involved a seller who had promised retiree health
in a collective bargaining agreement, and an asset buyer; the court held that
the buyer would be subject to the retiree health obligation, since by
continuing the operations the retiree health obligation would continue, and
expanded ERISA successor liability is not limited only to ERISA delinquent
multiemployer contributions or withdrawal liability but applies also to ERISA
fiduciary duties and to promises for retiree health; the court denied the
motion to dismiss claims).

[43]  Watson
v. Deaconess Waltham Hospital
, 298 F.3d 102, 110 (1st Cir. 2002) (noting
that with regard to the suits for breach of fiduciary duty under ERISA §409(
b), nothing in ERISA precludes a later fiduciary from assuming by contract the
ERISA obligation of the former fiduciary); Bish v. Aquarion Services
Co.
, 289 F. Supp. 2d 134 (D. Conn. 2003) (a seller promised retiree
discussed above; court noted in dictum that ERISA fiduciary duties under ERISA
§409 apply to a buyer who has assumed the plan obligations in a collective
bargaining agreement).

[44] See
also: EEOC v. MacMillan Bloedel Containers, 503 F.2d 1086 (6th Cir.
1974) (court held that the considerations justifying a successor doctrine to
remedy unfair labor practices in Golden State Bottling Co. would
also apply to unfair employment practices under Title VII, and therefore
successor liability would apply where there was substantial continuity of the
business operations and the successor had prior notice of the claim); Teed
v. Thomas and Betts Power Solutions
, 711 F.3d 763 (7th Cir. 2013) (court
imposed successor liability on asset purchaser for seller’s FLSA violations for
unpaid overtime despite contractual language excluding the assumption of this
liability.

[45] Musikiwamba
v. ESSI, Inc
., 760 F.2d 740 (7th Cir.1985) (broadened successor liability
doctrine was applicable in the case of employment discrimination suits);
E.E.O.C. v. Northern Star Hospitality, Inc., 777 F.3d 898 (7th Cir. 2015)
(expanded successor liability was applied in liability for Title VII employment
discrimination since successor had notice of the pending lawsuit; successor but
not predecessor could provide relief after the sale or dissolution, and there
was continuity of operations and work force of the predecessor and successor).

[46] 
NLRA §8, 29 U.S.C.A. §158.

[47]  Fall
River Dyeing & Finishing Corp. v. N.L.R.B.
, 482 U.S. 27, 107 S. Ct.
2225, 96 L. Ed. 2d 22 (1987) (a company that was liquidating sold its remaining
assets and rehired a number of employees; the company refused to bargain with
the union, claiming that it was not a successor; the Supreme Court held that
where a majority of the company’s employees have worked for the predecessor,
and there was a substantial continuity—which depends on whether the business is
substantially the same, the employees were doing the same jobs, and the
business was producing the same products—the new employer has a duty to bargain
in good faith with the union but is not bound to the specific provisions of the
existing union agreement).

[48] 
See, N. L. R. B. v. Burns International Security Services, Inc.,
406 U.S. 272, 284, 291, 92 S. Ct. 1571, 1580, 1584 (1972) (even where
successors held to be legal successor for purposes of bargaining, this alone is
insufficient to bind the successor to the substantive provisions of the
predecessor employer’s collective bargaining agreement with the union); Howard
Johnson Co. v. Detroit Local Joint Executive Board
, 417 U.S. 249, 258 n. 3,
94 S.Ct. 2236, 2241 n.3 (1974) (not bound to substantive provisions even if it
is a legal successor for purposes of bargaining, even in the presence of a
clause binding successor and assigns to the terms of that agreement).

[49]  See,
e.g.,
 Teamsters Pension Trust Fund of Phila. v. Littlejohn, 155
F.3d 206 (3d Cir. 1998) (discussed above; liability for delinquent pension
contribution after a merger).

[50]  See,
e.g.,
 In re Challenge Stamping and Porcelain, 719 F.2d 146
(6th Cir. 1983) (corporation that acquired 100% of stock of sponsoring
corporation one month after it filed for bankruptcy was not considered part
controlled group for pension plan’s underfunding because purpose of ERISA
termination liability is to avoid employer abuse of plan termination insurance
and Congress did not intend to extend the liability to corporations that made
contingent purchases of stock that had no practical effect; purchase of stock
during bankruptcy for  one dollardoes not make party part of controlled
group since stock is worthless; therefore, a purchase from the bankruptcy estate
does not by itself bring successor liability); PBGC v. Ouimet Corp.,
711 F.2d 1085 (1st Cir. 1983), cert. denied 464 U.S. 961, 104
S. Ct. 393 (1983) (where subsidiary went bankrupt and terminated underfunded
plan after acquisition by controlled group that included another bankrupt
subsidiary, termination liability was allocated only to the solvent group members,
and not bankrupt corporations’ estates, since applying the bankrupt’s assets to
PBGC’s liability would have reduced assets available to their creditors and
inequitably benefited group members; court noted that ERISA provides a lien on
30% of the net worth, not asset value and a bankrupt corporation has negative
net worth). See also Brighton, How Free is Free and
Clear
, 21 SEP Am. Bankr. Inst. J. 1 (Sept. 2002).

[51]  Chicago
Truck Drivers, Helpers & Warehouse Workers Union Pension Fund v. Tasemkin,
Inc.
, 59 F.3d 48 (7th Cir. 1995) (Seventh Circuit held that claim by
multiemployer pension fund against successor entity for ERISA withdrawal
liability and delinquent pension contributions to the union’s pension should
not have been dismissed; court notes that it was not absolutely precluded from
finding successor liability against the successor where there was substantial
continuity of operations and notice, despite the fact that company had just
emerged from bank­ruptcy; successor liability after bankruptcy does not subvert
bankruptcy rules since the property has already emerged from bankruptcy).

[52] 
In Plumbers, Pipefitters and Apprentices Local Union No 112 v. Mauro’s
Plumbing, Heating and Fire Suppression
, Inc., 84 F. Supp. 2d, 344 (N.D.
N.Y. 2000) the Northern District of New York held that where plumbing company that
signed collective bargaining agreement ceased operations and owners established
a non-union company (Northeast Mechanical) three months later at the same
location, the successor was liable for the predecessor’s multiemployer welfare
contributions as the alter ego of the first company since there was continuity
of ownership and management, and employment of many of the same employees,
similarity of business purposes, overlapping operations, use of office and
plumbing equipment and sharing of customers. (Because it found alter-ego
status, court found it unnecessary to also examine successor liability status).

[53]  See,
e.g.,
 Solar v. Pension Benefit Guaranty Corporation, 504 F.
Supp. 1116 (S.D. N.Y. 1981), aff’d, 665 F.2d 28 (2d Cir. 1981)
(holding that a transaction intended to avoid liability should be disregarded
for Title IV liability purposes). See also In Re Consolidated
Litigation Concerning International Harvester’s Disposition of Wisconsin Steel
,
681 F. Supp. 512 (N.D.Ill. 1988) (International Harvester) (predecessor that
sold business with principal purpose of evading liability and delegated pension
obligations to purchaser that at time lacked reasonable chance of meeting this
obligation was held liable to the PBGC for the unfunded benefit payments owed).

[54] 
One of the transactions that persuaded Congress to enact ERISA §4069 was the
sale by International Harvester of a financially crippled subsidiary, Wisconsin
Steel, which sponsored grossly underfunded pension plans, to a financially weak
buyer. See International Harvester, above. The PBGC brought suit to
preclude International Harvester from avoiding liability for the terminated
plans by reason of that transaction and the court eventually upheld the PBGC’s
claims. Nevertheless, while that case was pending, Congress enacted ERISA §4069
because it felt that such a provision was necessary to deter “abusive schemes”
to avoid liability “which can lead to complex, costly litigation.” H. Rep. No.
99-241, Pt. 2, 99th Cong., 1st Sess., reprinted in 1986 U.S. Code Cong. &
Admin. News 685, 713 (House Report).

ERISA §4069 “incorporates court decisions under current
law by adding explicit statutory language to make clear that transactions, a
principal purpose of which is to evade liability under the statute, are to be
ignored in deter­mining liability.” House Report. It is arguable that if an
entity was not in the controlled group of the plan before the transaction, it
could not be held liable under §4069 since §4069 only operates to ignore the
transaction.

[55] ERISA
§4212(c).

[56]  See Central
States Pension Fund v. Georgia-Pacific LLC
, 639 F.3d 757 (7th Cir. 2011)
(ERISA §4204 contract will avoid withdrawal liability and sale of one division
was not culmination of withdrawal by stages from multiemployer plan; withdrawal
was solely because of employer’s sale of its last division in which buyer
assumed employer’s liability for contributions in the ERISA  §4204
transaction).

[57] ERISA
§4204(a)(2).

[58] ERISA
§4204(a)(3)(A).

[59] ERISA
§4204(b).

[60]  Artistic
Carton Co. v. Paper Industry Union—Management Pension Fund
, 971 F.2d 1346
(7th Cir. 1992) (arbitrator did not err in finding that a multiemployer pension
plan properly assessed withdrawal liability on a successor employer based on
the predecessor employer’s contributions since ERISA §4204 does not necessarily
imply that there will never be withdrawal liability for asset buyers who do not
sign a ERISA §4204 contract, and the multiemployer plan documents specifically
provided that withdrawal liability would include all service of the employees
including service with the predecessor employer).

https://drive.google.com/file/d/1Dqz-DUXo2DinSEth5jl3srUU1GB4ipCZ/ 
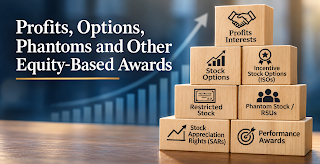
Categories
Blog

Rev. Proc. 2021-30 (EPCRS Update)


Rev. Proc. 2021-30 (EPCRS Update)

Charles C. Shulman, Esq.

Rev. Proc. 2021-30 updates the IRS Employee Plans Compliance Resolution System (EPCRS) Program, with the following changes to the EPCRS program: 

(i)  the end of the self-correction period for significant failures is extended by an extra
year; 

(ii) an anonymous VCP with a free VCP pre-submission conference
procedure is provided instead of John Doe applications; 

(iii) the plan sponsor can correct an operational
failure under SCP by retroactive plan amendment if the amendment will result in
an increase of a benefit, right or feature (BRF) is allowed even if such BRF is not
available to all eligible employees, provided the benefiting group satisfies
the IRC’s nondiscrimination rules; 

(iv) it extends by three years the sunset of
the safe harbor correction method for employee elective deferral failures
associated with missed elective deferrals for participants who have an
automatic contribution feature to December 31, 2023; 

(v) it expands the de
minimis exception from the requirement to seek recovery from overpayment
recipients for small overpayments with such amount being increased from $100 to
$250; 

(vi) it allows entering into payment agreements with participants who
were overpaid; and

(vii) it includes two new benefit overpayment correction methods
for defined benefit plans
that encourage employers to avoid seeking recoupment of
benefit overpayments made to participants
which are based on a plan’s funding status by either not requiring
correction if the specified funding levels are met (the funding exception
contribution method) or by limiting the amount to be recouped under certain
circumstances (the contribution credit correction method).

If you have any questions, please contact Charles at cshulman@ebeclaw.com or at 201-357-0577

Categories
Blog

Missing Plan Participants – Recent Guidance


Missing Plan Participants – Recent Guidance


Charles C. Shulman, Esq.


March 31, 2021
(Revised Aug. 2021)


A common problem in plan administration is finding missing
participants. Sometimes these lost participants simply cannot be located. Other
times they can be located but they do not accept distribution packages with
respect to their benefits.  


Field Assistance Bulletins. 

DOL Field Assistance Bulletin 2004-02 stated that certain methods of finding participants be used because they have a high
degree of success and are relatively inexpensive. These methods are as follows:
(i) certified mail, (ii) plan records of participants in other plans maintained
by the employer, for example, a health plan, (iii) using a designated
beneficiary to locate a participant, (iv) using the IRS or Social Security
Administration letter-forwarding service.  However, both these letter
forwarding programs were discontinued (the IRS program in 2012 and the SSA
program in 2014).

DOL Field Assistance Bulletin 2014-1 sets forth the DOL’s
current views on the proper fiduciary steps to follow in connection with
locating missing participants. It prescribes the search steps that must be used
in locating the lost participant. Routine methods of regular mail or email will
suffice most of the time. However more may be necessary if there is no response
or the fiduciary believes it does not have a current address. Certified mail
should be used to find out if the participant can be located. FAB 2014-1 notes that
the DOL model participant notice for plan termination can be used. A search of
the employer records including plan records for other plans maintained by the
employer such as health plans should be done. Asking designated beneficiaries
of the participant for the location of the participant should be done. Use of
free internet search tools such as Internet search engines, public record
databases, obituaries and social media should be utilized. Possible additional
searches include internet search tools that charge a fee, commercial locator
services, credit reporting agencies and investigative databases. If a participant
still cannot be located, the preferred method of distributing the account from
the plan is to establish an IRA rollover account following the general
procedure for distribution of cash-out amounts between $1,000 and $5,000. This
amount would be rolled over to an IRA which would be invested in an investment
designed to preserve principal and provide a reasonable rate of return. There
is a strong preference for rollover distributions because if funds are
otherwise distributed, there will need to be 20% mandatory withholding.
 Another alternative is to furnish the funds to the state unclaimed property fund. Many states
maintain funds with web internet access sites listing the names of individuals
who are due funds from one source or another. Some state funds accept plan distributions on behalf of missing participants. Although the Department of
Labor in Opinion 94-41A takes the position that state funds may not be
automatically escheated to the state, the fiduciary may reach the conclusion
that this is the proper course of action where it is necessary to distribute
all funds in order to complete the termination of the plan.


DOL Best-Practices Memo. A DOL “best practices” memo – “Missing Participants – Best
Practices for Pension Plans,” (January 12, 2021), www.dol.gov/agencies/ebsa/employers-and-advisers/plan-administration-and-compliance/retirement/missing-participants-guidance/best-practices-for-pension-plans,
outlines how fiduciaries of defined benefit plans and defined contribution
plans can handle missing participants. The Best Practices memo outlined
red flags that the DOL looks for as indicators of missing participant issues,
including: a significant number of participants who are nonresponsive, a significant number of terminated vested participants reaching normal retirement
age who have not started receiving benefits, incomplete contact information and
census data and absence of sound policies for handling returned mail and
uncashed checks. The 2021 Best Practices memo also gives examples of best
practices, including:

  1. Maintaining accurate
    census information for the plan’s participant population (including
    contacting participants and beneficiaries on a periodic basis to confirm
    or update their contact information, including contact information change
    requests in plan communications, flagging undeliverable mail/email and
    uncashed checks, requesting updates to contact information for
    beneficiaries, regularly auditing census information, and in the case of a
    change in record keepers or plan sponsor, addressing the transfer of appropriate
    plan participant and beneficiary information and relevant employment
    records);
  1. Implementing effective
    communication strategies (including using plain language and offering
    non-English assistance, encouraging employees to notify the plan of any
    change in contact information and encouraging information contact through
    plan websites and toll-free numbers, building steps into plan enrollment
    for new employees and exit procedures for separating employees to confirm
    or update contact information, communicating options about consolidating
    accounts from prior employer plans and marking correspondence with the
    original plan or sponsor name where this has changed after participants
    separated);
     
  1. Conducting missing
    participant searches (including checking plan and employer records for
    participant, beneficiary and emergency contact information, checking with
    designated plan beneficiaries and emergency contacts for updated contact
    information, using free online search engines, public record databases,
    obituaries, and social media to locate individuals, using a commercial
    locator service or credit-reporting agency to locate individuals, mailing
    certified mail or mail with tracking features to the last known mailing
    address, attempting contact via email addresses telephones and social
    media, searching death Indexes, contacting colleagues of missing
    participants or by publishing a list of missing participants on the
    company’s intranet, reaching out to a union’s local offices and
    registering and publicizing missing participants on public and private
    pension registries with privacy and cyber security protections); and 
  1. Documenting procedures
    and actions (including putting applicable plan policies in writing,
    documenting key decisions and the steps taken to implement the policies,
    ensuring third-party record keepers are performing agreed upon services,
    and working with the record keeper to identify and correct shortcomings in
    the plan’s recordkeeping and communication practices).


PBGC Missing Participant Program for Terminating Defined Benefit
and Defined Contribution Plans
. Under the Pension Protection Act of 2006, the
single-employer missing participant program required to be maintained by the
PBGC is extended to terminating single-employer and multiemployer pension plans
and defined contribution plans, and defined benefit pension plans that are not
covered by the PBGC because they have no more than 25 active participants.
ERISA § 4050(d). In December 2017, the PBGC finalized regulations first
proposed in 2016 that expand its existing Missing Participants Program to cover
terminated 401(k) and other defined contribution plans and defined benefit
plans that are not currently covered by the program. PBGC Reg. §§ 4050.101 to
4050.407, 82 Fed. Reg. 60800 (Dec. 22, 2017). Under ERISA § 4050 as amended by
PPA 2006, the PBGC is required to operate a missing participants program for
single-employer plans and multiemployer plans covered by Title IV of ERISA. It
also may maintain an optional program for defined benefit plans not covered by
Title IV of ERISA and for defined contribution plans. The regulations establish
missing participant programs for terminating multiemployer defined benefit
plans covered by Title IV (PBGC Reg. §§ 4050.401 to 4050.407), terminating
professional service employer defined benefit plans not covered by Title IV
(PBGC Reg. §§ 4050.301 to 4050.307), and for terminating defined contribution
plans (PBGC Reg. §§ 4050.201 to 4050.207). The regulations also make changes in
the existing Missing Participants Program including providing for (i) fees to
be charged for plans to participate in the Missing Participants Program; (ii) a
requirement to treat as missing certain nonresponsive distributees with de
minimis benefits subject to mandatory cash-outs under the Plan’s terms; (iii)
stricter requirements for diligence searches, including sponsor and related
plan records, free web search methods and commercial locater services; (iv)
fewer benefit categories and fewer sets of actuarial assumptions for
determining the amount to transfer to the PBGC; and (v) changes in the rules
for paying benefits to missing participants and their beneficiaries. The
program is mandatory for PBGC for single-employer plans and multiemployer plans
subject to Title IV and insured by the PBGC. The insured defined benefit plans
are required to either (i) transfer the benefits of missing participants to the
PBGC, or (ii) purchase annuities and provide the PBGC with information about
the annuity provider. PBGC Reg. §§ 4050.103 and 4050.403. Participation in
the Missing Participants Program for defined contribution plans and defined
benefit plans not covered by PBGC insurance is voluntary.

A defined contribution plan program that participates in PBGC’s
Missing Participants Program must either (i) transfer accounts of missing
participants to the PBGC, or (ii) send the PBGC information about where the
accounts of its missing participants were transferred. PBGC Reg. §§ 4050.203
and 4050.303. As part of the Missing Participants Program, the PBGC is
creating a database that may be used to provide information about missing
participants and their benefits. It would permit the public to search the
database to determine whether it contained information about benefits available
to a specific participant, but it would be designed in a way that would protect
individuals’ privacy. A one-time fee, $35 initially, is charged for
transferring a participant’s defined benefit or defined contribution benefit to
the PBGC. Amounts of $250 or less could be transferred at no fee. The
regulations are effective January 22, 2018, and apply to single-employer plans
terminating after 2017 and to the closeout of multiemployer plans after 2017.         

DOL Field Assistance Bulletin 2021-01,
“Temporary Enforcement Policy Regarding the Participation of Terminating
Defined Contribution Plans in the PBGC Missing Participants Program” (January
12, 2021) provides that the DOL will not pursue violations under ERISA §404(a)
against plan fiduciaries of a terminating defined contribution plan (or a
qualified termination administrator of an abandoned plan) in connection with
the transfer of missing participants’ account balances to the PBGC in
accordance with the PBGC’s missing participant regulations (PBGC Reg.
§4050.101; discussed above), rather than to an IRA, certain bank accounts or the
state unclaimed property fund per DOL Reg. §2550.404a-3, if the plan fiduciary
complies with the guidance in this Field Assistance Bulletin and has generally
acted in accordance with a good faith reasonable interpretation of ERISA §404.
(This does not preclude the DOL from pursuing violations under ERISA for a
failure to diligently search for participants prior to the transfer of their account
balances to the PBGC.) The plan fiduciary who participates in the PBGC Defined
Contribution Missing Participants Program must otherwise comply with the
requirements of the safe harbor regulation at DOL Reg. §2550.404a-3 for
distributions from terminated plans. Notices to participants must state that
their account balances are being transferred to the PBGC’s Defined Contribution
Missing Participants Program, and include the PBGC’s website and contact
telephone number. A plan fiduciary can also transfer to the PBGC the account
balances of participants who elected a lump-sum distribution of the entire
account under the terms of the plan if that distribution was paid by check and
the check remains uncashed after the cash-by date prescribed on the check (or 45
days if longer). A plan fiduciary may pay the PBGC charge from the accounts
transferred to the PBGC Defined Contribution Missing Participants Program
unless the plan prohibits such payment from the plan.


If you have any questions regarding the above, contact Charles C.
Shulman, Esq. at 
cshulman@ebeclaw.com or at 201-357-0577.


Categories
Blog

American Rescue Plan Act of 2021 – Summary of Benefit Provisions


March 15, 2021

American Rescue Plan Act of 2021 – Summary of Benefit
Provisions

Charles C. Shulman, Esq.

 A.  Introduction  – The American Rescue Plan Act of 2021 (“ARPA”), H.R.
1319, P.L. 117-2, signed March 11, 2021, which provides COVID-19 relief to
governments, businesses and individuals, also provides relief to plan sponsors
and participants of employee benefit plans, including: (i) actions to address
underfunded multiemployer pension plans; (ii) extended amortization for single
employer pension plans; (iii) a 100% subsidy of COBRA premiums for a six month
period beginning April 1, 2021; (iv) an increase in the dependent care
assistance program limit; and (v) broadening of the definition of covered
employee for purposes of Internal Revenue Code § 162(m).

B.   Multiemployer Plan Provisions

      1. Delay of Designation of
Multiemployer Plan Funding Status in 2020 and 2021
– Under the
American Rescue Plan Act of 2021 (“ARPA”)
(3-11-2021)
§ 9701(a)(1) if a multiemployer
defined benefit plan elects, the funding status as endangered, critical, or
critical and declining status under IRC § 432 for plan years beginning on or
after March 1, 2020 and, if elected, the next succeeding plan year, may generally
remain the same as in the plan year beginning on or after March 1, 2019.  ARPA § 9701(a)(2) provides that where such an
election is made for a plan that was in endangered or critical status, the plan
is not required to update its funding improvement or rehabilitation plan and
schedules under IRC § 432(c)(6) and 432(e)(3)(B) until the plan year following
the plan year(s) elected.  The election (which
must be made in accordance with guidance from the Secretary of the Treasury) must
be included in the annual certification or made within 30 days after the annual
certification.  ARPA § 9701(c)(1).  Such an election may be revoked only with the
consent of the Secretary of the Treasury. 
Notice must be given to participants that such an election has been
made.  ARPA § 9701(c)(2).  These provisions are effective on the date of
enactment, i.e., March 11, 2021.  These
provisions and some of ones below are similar to those made 2008 financial
crisis legislation.

      2.  Temporary
Extension of Funding Improvement and Rehabilitation Periods for Multiemployer
Pension Plans in Critical and Endangered Status in 2020 or 2021
–  The
American Rescue Plan Act of 2021 (“ARPA”)
(3-11-2021)
§ 9702(a) provides that if a multiemployer
defined benefit plan that is in endangered or critical status for a plan year
beginning in 2020 or 2021, the plan sponsor may elect to extend the plan’s
otherwise applicable 10 year funding improvement period for endangered plans
under IRC § 432(c) or 10 year rehabilitation period for critical plans under
IRC § 432(e) by five years, from 10 to 15 years. If a multiemployer defined
benefit pension plan is in seriously endangered status for a plan year
beginning in 2020 or 2021, the plan sponsor may elect to extend the plan’s
otherwise applicable funding improvement period by five years from 15 to 20
years.  The election is to be made at
such time, and in such manner and form, as the Secretary of the Treasury may
prescribe in consultation with the Secretary of Labor.  ARPA § 9702(b)(1).  This provision is effective for plan years
beginning on or after January 1, 2020. 
ARPA § 9702(c). 

      3.  Easing
of Funding Standard Account Rules for Multiemployer Plans
– The
American Rescue Plan Act of 2021 (“ARPA”)
(3-11-2021)
 § 9703 adds new IRC § 431(b)(8)(F) allowing an
underfunded multiemployer pension plan that meets the solvency test under IRC §
431(b)(8)(C), to use either one or both of two special funding relief rules
which apply generally for the first two plan years ending on or after March 1,
2020:

    First – Amortization
of net investment losses – The plan sponsor may make changes to the plan’s
funding standard account to treat the portion of its experience loss
attributable to the net investment losses or to any COVID-19-related losses (in
the two plan years ending on or after March 1, 2020) be amortized in equal
annual installments over a 30-year period instead of a 15-year period.  IRC § 431(b)(8)(F)(i) (modifying §
431(b)(8)(A)(I)(i)); ARPA § 9703.

    Second – Expanded
smoothing period and asset valuation corridor – A multiemployer plan may change
its asset valuation method in a manner that spreads the difference between the
expected returns and actual returns for the first two plan years ending on or
after March 1, 2020.  IRC § 431(b)(8)(F)(i)
(modifying § 431(b)(8)(B)(I)(i)); ARPA § 9703. 
In addition, the plan’s asset value must be adjusted under the valuation
method being used so the value of plan assets is not less than 80% of the
current fair market value of the assets and not more than 130% of the current
fair market value (rather than 120%). IRC § 431(b)(8)(F)(i) (modifying §
431(b)(8)(b)(I)(i)); ARPA § 9703.

Under IRC
§ 431(b)(8)(C), the “solvency test” is met only if the plan is
projected to have sufficient assets to timely pay expected benefits and
anticipated expenditures over the amortization period, taking into account the
special funding rule changes.
 

      4.   Temporary
Special Financial Assistance for Financially Troubled Multiemployer Pension
Plans
– Under new ERISA § 4262 added the
American Rescue Plan Act of 2021 (“ARPA”)
(3-11-2021)
§ 9704 the PBGC will provide financial
assistance (without any requirement of repayment) to “eligible
multiemployer plans” upon request by the plan sponsor.

            a.   Eligible
Multiemployer Plan
– A plan is an “eligible multiemployer plan” if:
(i) it is in critical and declining status in any plan year beginning in 2020
through 2022; (ii) a suspension of benefits for the plan under the
Multiemployer Pension Reform Act of 2014 has been approved as of
March 11, 2021; (iii) in any plan year beginning in 2020 through 2022, the plan is in
critical status, has a modified funded percentage of less than 40%, and has a
ratio of active to inactive participants which is less than two to three; OR
(iv) the plan became insolvent after December 16, 2014, has remained insolvent,
and has not been terminated as of March 11, 2021.  IRC § 4262(b) added ARPA § 9704.

            b.   Application
for special financial assistance
– PBGC regulations/guidance will provide
the requirements for special financial assistance applications. The PBGC may
also provide in regulations or guidance that during a period no longer than the
first two years following the date of enactment applications may not be filed unless
(i) the plan is insolvent or is likely to become insolvent, (ii) the plan is
projected by the PBGC to have a present value of financial assistance payments
that exceeds $1 Billion if the financial assistance is not provided, (iii) the
plan has implemented benefit suspensions as of the date of enactment or (iv) the
PBGC determines it appropriate based on other similar circumstances.  New IRC § 4262(c).  Any application by a plan for special
financial assistance must be submitted no later than December 31, 2025, and any
revised application must be submitted no later than December 31, 2026.  .  IRC §
4262(f).

            c.   Actuarial
assumptions
– For purposes of eligibility for the special financial
assistance, the PBGC will accept assumptions incorporated in the plan’s
determination that it is in critical status or critical and declining status
for certifications completed before January 1, 2021, unless such assumptions
are clearly erroneous. For certifications of plan status completed after
December 31, 2020, a plan determines whether it is in critical or critical and
declining status for purposes of eligibility for special financial assistance
by using the assumptions that the plan used in its most recently completed
certification of plan status before January 1, 2021, unless such assumptions are
unreasonable.  IRC § 4262(e) added ARPA §
9704.

            d.   Amount
and manner of payment of special financial assistance
– Special financial
assistance is issued by the PBGC in lump sum within one year to an eligible
multiemployer plan is effective no later than 1 year after a plan’s special
financial assistance application is approved. 
New IRC § 4262(i).

            e.   Reinstatement
of suspended benefits
– An eligible multiemployer plan that receives
special financial assistance must reinstate any benefits that were suspended.  New IRC § 4262(k).

            f.    Required
disclosure
– An eligible multiemployer plan receiving special financial
assistance must provide each participating employer and labor organization
employer, if applicable, an estimate of the employer’s share of the plan’s
unfunded vested benefits as of the end of each plan year ending after the date
of enactment of the proposal.  This
disclosure must include a statement that, due to the special financial
assistance, the plan will have sufficient resources to pay 100% of the plan’s
benefit obligations until the last day of the plan year ending in 2051.

            g.   Appropriations
– ARPA establishes an eighth fund for special financial assistance to
multiemployer plans and to pay for PBGC’s necessary administrative and
operating expenses relating to such special financial assistance.  ERISA § 4005(i)(1) added ARPA § 9704(a).

      5.   PBGC
premium rate increase to $52 for multiemployer plans in 2031 subject to future COLA
adjustments
  – For plan years
beginning after December 31, 2030, the flat rate PBGC premium for multiemployer
plans will increase to $52 per participant and will be subject to
cost-of-living adjustments for plan years beginning in a calendar year after
2031 in multiples of $1, up from the flat rate of $31 per participant currently
in effect.  American Rescue Plan Act of
2021 (“ARPA”) (3-11-2021) § 9704(c) 4262(c) adding ERISA §§
4006(a)(3)(A)(viii) & 4006(a)(3)(N).


C.   Single-Employer Plan Changes

      1.   Extended
Amortization of Funding Shortfalls for Single-Employer Plans
– When a
single-employer plan has a funding shortfall, IRC § 430(c)(2) provides that the
plan must establish a shortfall amortization base to be paid over a 7-year
amortization period.  The
American Rescue Plan Act of 2021 (“ARPA”)
(3-11-2021)
 amends IRC § 430 to provide that, with respect
to plan years beginning on or after January 1, 2020 (or, if so elected, on or after
January 1, 2019) the shortfall amortization bases for all plan years preceding
the first plan year beginning on or after January 1, 2020 (or January 1, 2019,
if so elected), and all shortfall amortization installments determined with
respect to such bases, are reduced to zero. IRC § 430(c)(8) added by ARPA §
9705.  In addition, the funding shortfalls,
as redetermined for plan years beginning on or after January 1, 2020 (or, if
elected, on or after January 1, 2019) are determined over a 15-year period,
rather than a 7-year period. IRC § 430(c)(8) added by ARPA § 9705.  This is effective for plan years beginning on
or after January 1, 2019.

      2.   Extension
of Pension Funding Stabilization Percentages for Single Employer Plans
– In
connection with the 25-year pension interest rate smoothing enacted in 2012 and
later legislation to alleviate high pension funding obligations, the interest
rate used must be within 10% of the 25-year interest rate averages.  Also, the smoothed interest rates were scheduled
to begin phasing out in 2021.  The
American Rescue Plan Act of 2021 (“ARPA”)
(3-11-2021)
§ 9706 extends the pension
funding stabilization percentages through 2029. 
The specified percentage range for a plan year is: (i) 90 percent to 110%
for 2012 through 2019, (ii) 95% to 105% for 2020 through 2025, (iii) 90% to 110%
for 2026, (iv) 85% to 115% for 2027, (v) 80% to 120% for 2028, (vi) 75% to 125%
for 2029, and (vii) 70% to 130% for 2030 or later. IRC §
430(h)(2)(C)(iv)(II) as amended by
ARPA
§ 9706(a). A 5% floor is established on the 25-year
interest rate averages. IRC §
430(h)(2)(C)(iv)(I) as amended by ARPA
§ 9706(b). This is effective for plan years beginning
on or after January 1, 2020.


D.   ARPA Health Plan Changes in 2021

      1.   COBRA
100% Premium Subsidy Between 4/1/2021 and 9/30/2021
 – The American Rescue Plan Act of 2021 (“ARPA”)
(3-11-2021)
§ 9501 provides
that for the period between April 1, 2021 and September 30, 2021, “a
ssistance-eligible individuals” (as defined below) may
receive a 100% subsidy (full premium payment) for
any premium required
for COBRA continuation coverage under a group health plan.  ARPA
§ 9501(a)(1).
 
These rules are effective March
11, 2021.

An “assistance-eligible
individual” is any COBRA qualified beneficiary who, with respect to a
period of coverage during the period beginning on April 1, 2021 and ending on
September 30, 2021 (1) is eligible for COBRA continuation coverage due to termination
of the employee (other than by reason of such employee’s gross misconduct or for
voluntarily quitting) or reduction of hours of employment, pursuant to IRC
§ 4980B(f)(3)(B), and (2) elects such coverage. ARPA § 9501(a)(3).

The above COBRA premium
assistance is excludible from the gross income of the individual under IRC
§ 139l added by ARPA.  COBRA continuation coverage that qualifies
for premium assistance also includes continuation coverage offered by a
State program that provides comparable continuation coverage. ARPA Committee
Report JCX-2-21.

A group health plan may provide
for special plan enrollment options (pursuant to a Section 125 cafeteria plan)
to assistance-eligible individuals allowing them to change coverage options
under the plan in conjunction with electing COBRA continuation coverage within
90 days of the date of notice of the enrollment option.  ARPA
§ 9501(a)(1)(B).  Eligibility for coverage under
another group health plan does not terminate eligibility for premium assistance
if the other group health plan coverage consists only of excepted benefits
under IRC
§ 9382(c)(2), is a
qualified small employer HRA or is a flexible spending arrangement.  ARPA
§ 9501(a)(1)(B)(ii)(IV).

Under ARPA there is a special
COBRA election period (for at least 60 days after notice is given) for a
qualified beneficiary who either (1) does not have an election of COBRA
continuation coverage in effect on April 1, 2021 but who would be an assistance-eligible
individual were such an election in effect, or (2) elected COBRA continuation
coverage and discontinued from such coverage before April 1, 2021.

Under ARPA the employer to whom
continuation coverage premiums are payable is allowed a credit for each
calendar quarter against Medicare tax due by the employer under IRC § 3111(b) in
an amount equal to the premiums not paid by assistance-eligible individuals for
COBRA coverage by reason of the subsidy during such quarter.  New IRC § 6432 added by ARPA
§ 9501(b)(1).

The COBRA notice that a plan
administrator is required to provide with respect to a qualifying event during
the period of April 1, 2021 to September 30, 2021 must contain certain
additional information regarding the right to the premium assistance under
ARPA.  ARPA
§ 9501(a)(5).

IRS
Notice 2021-31 provides Q&As regarding the ARPA COBRA premium
assistance provisions.

      2.   Temporary
Increase for 2021 of Dependent Care Assistance Program Limit
 – The American Rescue Plan
Act of 2021 (“ARPA”) (3-11-2021)
§ 9631 expands the child and dependent care
tax
credit available to taxpayers for tax
year 2021.
 Also, IRC § 129(a)(2)(D) as amended by ARPA §
9632(a) expand
s the annual
limit for
dependent
care
FSAs for 2021 only from $5,000 to $10,500 and from $2,500 to $5,250 for a married person filing separately.  This is effective for tax years beginning in
2021.  Any plan amendment must be made by
the last day of the plan year in which the plan amendment.  ARPA § 9632(c).  Note that the nondiscrimination testing rules
of IRC
§ 129(d) for dependent
care assistant programs
must still be met.

      3.   COVID-Related
Paid Sick Leave and Family Leave Credit
 – The Families First Coronavirus
Response Act of 2020 required certain employers to provide qualified paid sick
leave and family leave to employees who are unable to work due to COVID-19.  The costs were offset in part by refundable
tax credits for qualified leave payments from April 1, 2020 through December
31, 2020, and this was extended to March 31, 2021 by the Consolidated
Appropriations Act, 2021.  
The American Rescue Plan Act of 2021 (“ARPA”)
§ 9641 extends the emergency paid sick time and paid
family leave credits from April 1, 2021 through September 30, 2021.

      4.   Extension
of Refundable Premium Tax Credit for 2021 and 2022
 – A refundable
premium tax credit is available on a sliding-scale basis for individuals and
families with household income between 100% and 400% of the federal poverty
line who are enrolled in an Exchange-purchased qualified health plan, and who
are not eligible for other qualifying coverage. 
The
American Rescue Plan
Act of 2021
§ 9661 increases the premium tax
credit for 2021 and 2021 and also makes the premium tax credit available to
taxpayers whose income exceed 400% of the federal poverty line.  ARPA § 9662 provides that taxpayers do not
have to repay certain excess advance premium tax credit payments for 2020.  ARPA § 9663 provides for increased premium
tax credit for taxpayers receiving unemployment compensation in 2021.


E.   Expanded Class of Covered Employees under IRC § 162(m)

      IRC
§162(m) disallows a deduction by a publicly-held corporation for compensation
in excess of $1 million per year paid to a “covered employee.” “Covered
employee,” as amended by the Tax Cuts and Jobs Act of 2018, is an
individual serving as CEO, CFO and the next three highest compensated officers
who are required to be reported under the executive compensation disclosure
rules of the Securities Exchange Act of 1934. 
IRC §162(m)(3).  In addition, as
amended in 2018, if an employee is a covered employee for any prior tax year, the
employee’s compensation remains subject to the deduction limit in subsequent
tax years, even if the employee is no longer a covered employee. Id.

The American Rescue Plan Act of 2021 (“ARPA”)
(3-11-2021)
§ 9708 provides that for
taxable years beginning after December 31, 2026, “covered employee”
will also includes five other employees who are among the five highest
compensated employees (in addition to the top five executives described above).
IRC §162(m)(3)(C) as amended by ARPA § 9708. 
However, for these other five highest compensated employees, they will
not be considered covered employees for taxable years when they are no longer
among the top five highest compensated employees. IRC §162(m)(3)(D) as amended
by ARPA § 9708.  

Charles C. Shulman, Esq.
201-357-0577
cshulman@yahoo.com  

Categories
Blog

Taxpayer Certainty and Disaster Tax Relief Act of 2020 – Employee Benefit Provisions


Taxpayer
Certainty and Disaster Tax Relief Act of 2020 – Employee Benefit Provisions

The Taxpayer
Certainty and Disaster Tax Relief Act of 2020, enacted as part of the Further
Consolidated Appropriations Act, 2021, enacted December 27, 2020 (TCDTRA), provides
for the following: 

Special
Rules for Health and Dependent Care FSAs
. Under the Taxpayer Certainty and
Disaster Tax Relief Act § 214, with
respect to health and dependent care flexible spending arrangements:  (i) the health and dependent care FSAs may
provide for carryovers of unused account
balances from the 2020 plan year to 2021 and from the 2021 plan year to 2022)
and w
here the 2-1/2 month grace
period is used the plan can extend the grace period in 2020 and 2021 to 12
months instead of 2-1/2 months; (ii) h
ealth
FSA participants terminated in the middle of 2020 or 2021 can continue to
receive reimbursements from unused amounts through the end of the year;  (iii) t
he maximum age for dependent care
FSAs is extended by one year (age 13 instead of age 12) for dependents who age
out during the pandemic; and (iv) a
prospective mid-year election changes for health and dependent care FSAs is
allowed in 2021.

Partial Terminations.  Under § 209 of the Taxpayer
Certainty and Disaster Relief Act, a plan will not be treated as having a
partial termination during any plan year that includes the period from March
13, 2020 to March 31, 2021 if the number of active participants covered by the
plan on March 31, 2021 is at least 80% of the number of active participants
covered by the plan on March 13, 2020.

Coronovirus-Related
Distributions Extended to June 25, 2021
. The Coronavirus Aid,
Relief and Economic Security Act of 2020 (CARES Act) allowed individuals to
take penalty free in-service coronavirus-related distributions of up to
$100,000 from their retirement accounts between January 1, 2020 and December
31, 2020.
The Taxpayer Certainty and Disaster Tax Relief Act of
2020 (“TCDTRA”) § 302 extends the period for in-service
coronavirus-related distributions of up to $100,000 (in total) through June 25,
2021.

Plan Loan Repayments
Tolled for up to the later of One Year and June 25, 2021
. Similar to provisions in the CARES Act, the Taxpayer Certainty
and Disaster Tax Relief Act § 302(c)(3)
increases the maximum
dollar limit allowed for plan loans to “eligible employees” up to
$100,000 and 100% of the vested account balance for loans initiated
between December 27, 2020 and June 25, 2021.
Repayments
for existing plan loans with payment dates between
December 27, 2020 and June 25, 2021 may be delayed to the later of June 25, 2021 or
one year
, with subsequent loan payments to be appropriately adjusted
to reflect the extension and any interest accruing during the extension. With
respect to existing plan loans with payment dates is between
December 27, 2020 and June 25, 2021 repayments may be delayed to
the later of June 25, 2021 or one year,
with the repayment
period tolled for the duration of the one-year period and subsequent loan
payments to be appropriately adjusted to reflect the extension and any interest
accruing during the extension.

Recontribution of Hardship Distribution for Home Purchase
not used because of Disaster
. Under the Taxpayer Certainty and Disaster Tax
Relief Act
§ 302(b), where an individual received a
hardship distribution from a 401(k) or 403(b) plan that was used to purchase or
construct a principal residence in a qualified disaster area during the period
beginning 180 days before the first day of the qualified disaster period and
ending 30 days after the qualified disaster period and which was not used
because of the disaster, may be returned to the plan at any time within the
period which begins at any time within the first day of the period of
withdrawal and ends June 25, 2021 (180 days after the date of enactment).

Reduced Minimum Age
for Pension Plan In-Service Distributions for Employees in the Building and Construction
Industries
. The SECURE Act amended Code § 401(a)(36) which allows in-service
distributions from defined benefit plans at age 59-1/2 rather than age 62. The Taxpayer
Certainty and Disaster Tax Relief Act amended Code § 401(a)(36) to provide that
pension plans may allow certain employees in the building and construction
industries who are not separated from employment to begin taking distributions
at age 55.

Amendment Deadlines. The Taxpayer Certainty and Disaster Tax Relief Act changes that are effective in 2020 would require to be
reflected in plan amendments by 12/31/2021, and TCDTRA changes that are
effective in 2021 would require to be reflected in plan amendments by
12/31/2022.

Categories
Blog

Coronavirus Aid, Relief and Economic Security Act (the CARES Act) of 2020


Coronavirus Aid, Relief and Economic Security Act (the “CARES
Act”)

 The Coronavirus Aid, Relief and
Economic Security Act (the “CARES Act”), enacted March 27, 2020,
provides, with respect to
employees and families impacted by the coronavirus
outbreak, for in-service plan distributions up to
$100,00 and increased plan loans to $100,000 (the coronavirus-related
distribution (“CRD”) and otherwise broadens the qualified plan loan
rules for affected employees.  The CARES
Act also waives required minimum distributions (“RMDs”) from defined
contribution plans and IRAs for 2020.

1.     
Coronavirus-Related
Expansion of Plan Loan Rules
.  The CARES Act allows plans to increase the
maximum dollar limit allowed for “eligible employees” under the IRC from
$50,000 to $100,000 between March 27, 2020 and 180 days later, i.e., September
23, 2020.  CARES Act § 
2202(b)(1)(A).  In addition, the CARES
Act allows an individual to take a plan loan up to 100% of such individual’s
vested accrued benefit, whereas previously this was limited to 50%.  CARES Act §  2202(b)(1)(B). 

In
addition, “eligible employees” with existing plan loans from a
qualified employer plan that’s due date is between March 27, 2020 and December
31, 2020, may be provided with a one year extension with the existing mandatory
repayment period tolled for the duration of the one-year period, and with
subsequent loan payments to be appropriately adjusted to reflect the one-year
extension and any interest accruing during the one-year extension.  CARES Act §  2202(b)(2).

An
“eligible employee” for this purpose is an individual: (a) who is
diagnosed with coronavirus; (b) whose spouse or dependent is diagnosed with
coronavirus; or (c) who experiences adverse financial consequences as a result
of being quarantined, being furloughed or laid off, having reduced hours, being
unable to work due to lack of child care, closing or reduced hours of a
business owned or operated by the participant or other factors determined by
the Secretary of the Treasury.  CARES Act
§§  2202(b)(3) & 2202(a)(4)(ii).

2.    Coronavirus-Related
Distributions Made in 2020
.  In an effort to provide liquidity to
individuals during the COVID-19 pandemic, the CARES Act allows individuals to
take penalty free in-service coronavirus-related distributions from their
retirement accounts (including 401(k) and Roth deferrals) between January 1,
2020 and December 31, 2020, subject to the limitations discussed below.  CARES Act § 2202(a). 
Under normal circumstances, such distributions prior to age 59 ½ would
be subject to an early withdrawal penalty under IRC § 72(t) in addition to regular income withholding
taxes.  Distributions from IRAs are also
eligible for the coronavirus-related distribution.

A
coronavirus-related distribution for this purpose is a distribution from
eligible retirement plans (qualified plans, 403(b) plans, eligible 457(b) plans
or IRAs) up to $100,000 made between January 1, 2020 and December 31, 2020 to
an individual: (a) diagnosed with coronavirus, (b) whose spouse or dependent is
diagnosed with coronavirus or (c) who experiences adverse financial
consequences as a result of being quarantined, furloughed or laid off, having
reduced hours, unable to work due to child care, closing or reduced hours of a
business owned or operated by the individual or other factors determined by the
Secretary of the Treasury.  CARES Act § 2202(a)(4)(A). 

A
plan administrator may rely on an individual’s certification that the
individual meets the eligibility requirements for a coronavirus-related
distribution unless the administrator has actual knowledge to the
contrary.  CARES Act § 2202(a)(4)(B) and IRS
Q&As on Coronavirus-Related Relief for Retirement Plans and IRAs (May 4,
2020) Q&A 11.   

The
CARES Act allows for the inclusion of the amount in income to be spread over
three taxable years.  CARES Act § 2202(a)(5).   A coronavirus-related distribution is not
subject to the IRC § 72(t) 10%
additional tax on early distributions. 
CARES Act § 2202(a)(1).
Coronavirus-related distributions are also exempt from the 20% tax withholding
on eligible rollover distributions, but they would be subject to a 10%
nonperiodic payment withholding.   CARES
Act § 2202(a)(6).

An
individual who receives a coronavirus-related distribution from an eligible
retirement plan (including an IRA) may repay the amount to an eligible
retirement plan (or IRA) within three years of receiving the distribution
(assuming the plan accepts rollover distributions).  Such individual could make installments or a
lump sum repayments, but the amount cannot exceed the amount distributed.  CARES Act § 2202(a)(3). 
This provides the individual with the opportunity to rebuild their
retirement accounts.

The
CARES Act rules for distributions are optional, and plan sponsors can choose
not to adopt them.  However, IRS guidance
provides that even if an employer does not treat plan distributions as a
coronavirus-related distribution, a “qualified individual” may treat
a 2020 distribution that meets the requirements to be a coronavirus-related
distribution as coronavirus-related on the individual’s federal income tax
return.  IRS Q&As on
Coronavirus-Related Relief for Retirement Plans and IRAs, Q&A 9. 

A
“qualified individual” for this purpose means an individual: (i) who
is diagnosed with the coronavirus by a test approved by the Centers for Disease
Control and Prevention (CDC); (ii) whose spouse or dependent is diagnosed with
the coronavirus by a test approved by the CDC; (iii) who experiences adverse
financial consequences as a result of being quarantined, being furloughed or
laid off, or having work hours reduced due to the coronavirus; (iv) who
experience adverse financial consequences as a result of being unable to work
due to lack of child care due to the coronavirus; or (v) who experiences adverse
financial consequences as a result of closing or reducing hours of a business
that you own or operate due to the coronavirus. 

3.    Waiver of Required Minimum Distributions
in 2020
.   The CARES Act temporarily
waives the required minimum distributions for defined contribution plans or
IRAs for those who turned 70½ on or prior to December 31, 2019: (i) if 2019 is
the first year of attaining age 70-1/2 then for the April 1, 2020 distribution,
and (ii) for the annual minimum distributions due by December 31, 2020.  IRC §
401(a)(9)(I) as
added by CARES Act of 2020 § 2023.
Any
amounts distributed in 2020 would not be eligible for a rollover
distribution.  However, they can be
recontributed to the plan or IRA. Such relief is similar to the relief provided
in 2009.  The provision applies for
calendar years beginning after December 31, 2019.  

4.    Funding Relief. The
Coronavirus Aid, Relief, and Economic Security Act of 2020 gives single
employer plan sponsors more time to meet their funding obligations by delaying
the due date for any minimum required contributions including quarterly
contributions otherwise due during the 2020 calendar year (e.g., contributions
due April 15, 2020, July 15, 2020, and October 15, 2020) to January 1, 2021,
but with interest accruing from the original due dates.  CARES Act § 3608.

5.    Plan Amendment
Deadline
for Coronavirus-Related Rules
.  The deadline that CARES Act amendments can be
made is the end of the first plan year beginning on or after January 1, 2022 or
such later date as the Secretary of the Treasury sets.  CARES Act § 2202(c).