
Carried
Interest Holding Periods
Charles
C. Shulman, Esq.
Teaneck, NJ, 201-357-0577
cshulman@ebeclaw.com
Profits Interest at https://ebeclaw.com/2022/03/profits-interests.html
, profits interests have become an
increasingly popular type of equity-based award if the entity is taxed as a
partnership, as they avoid income tax or FICA tax on grant and vesting, and
yield long-term capital gains on sale if certain requirements are met. However,
in 2017 this was limited in the case of
profits interests (carried interest) for professional investors and real estate development for rental or investment to where the holding period
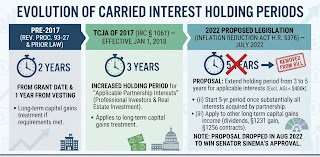
is three years. A 2020 legislative proposal in the pending Inflation Reduction Act to increase the holding period for such carried interest from three years to five years and to only begin only once substantially all the partnership interest subject to IRC § 1061 are acquired by the partnership. However, in further negotiations this proposal was taken out of the final bill.
Pre-2017 Holding Period for Profits Interests – Two Years from Grant and One Year from
Vesting. Prior to the enactment of the Tax Cuts & Jobs Act of 2017, generally
long-term capital gain treatment for profits interest would require the general
one-year holding period requirement (from the date the profits interests are
vested). In addition, Rev. Proc. 93-27 would require that the profits interests
be held for at least two-years after the date of grant.
Extended Holding Period for Professional Investors and
Real Estate Investment to Three
Years Under TCJA of 2017. Legislative
changes imposed by the Tax Cuts & Jobs Act of 2017 (effective January 1,
2018) enacted a new IRC § 1061, which imposes a three-year holding period (instead
of one year for ordinary capital gains) for an “applicable trade or
business,” if the partnership owns real estate for rental or investments,
since IRC § 1061, enacted by the Tax Cuts & Jobs Act of 2017 and effective
in 2018, in an effort to clamp down on “carried interest” use of
long-term capital gains tax rates for fund managers, provides that “applicable partnership interests” which
includes professional investors as well as those developing real estate for
rental or investment (IRC § 1061(c)(2)),
have an increased holding period for long-term capital gains treatment for
three years instead of one year. IRC §
1061(a).
2022 Proposed Legislation to Further Extend
Holding Period for Such Carried
Interest to Five Years, was Removed from the Bill to Win Approval from Sen. Krysten Sinema. Further legislative changes had been proposed in the Inflation Reduction Act in July 2022, H.R. 5376, as agreed to by Senator Charles Schumer and Senator Joe Manchin to amend
IRC § 1061 in the following ways: (i) the holding period for “applicable
partnership interests” which, under IRC § 1061(c)(2), includes carried interest for professional investors (e.g.,
private equity firms and hedge funds) and
real estate development for rental or investment, would be increased from three years to
five years (except with respect to taxpayers with adjusted gross income of less
than $400,000); (ii) the five-year holding period would begin only once substantially
all the partnership interest subject to §
1061 are acquired by the partnership; and (iii) the holding period would now apply
not just to profits interest but also to other income taxed as long-term
capital gains, including qualified dividend income included in net capital gain
for purposes of IRC § 1(h)(11), gain from the sale of active business assets
under IRC § 1231 and regulated futures contracts subject to IRC § 1256. However, it has now been reported on August 4, 2022 that Democrats are revising their Inflation Reduction Act in order to will approval from Senator Kyrsten Sinema (D. Arizona), which, among other things, would drop the proposed tax increase on carried-interest income. However, the carried interest tax change may appear in future legislation.
If you have any questions, please contact
me at cshulman@ebeclaw.com or 201-357-0577.