Trump’s Executive Order on Alternative Investments in 401(k) Plans:
Opportunities and Fiduciary Risks
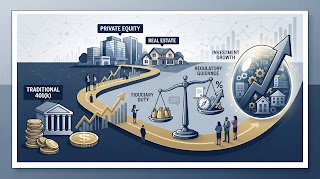
On August 7, 2025, President Trump issued Executive Order 14330, “Democratizing Access to Alternative Assets for 401(k) Investors,” directing the Department of Labor (DOL) to reconsider existing guidance and examine regulatory changes intended to facilitate investments in alternative assets through 401(k) plans.
Background: DOL Guidance Under the Trump and Biden Administrations
On June 3, 2020, during the first Trump administration, the DOL issued an Information Letter stating that ERISA does not categorically prohibit private equity investments as a component of a professionally managed asset allocation fund offered in a 401(k) plan. The DOL emphasized that the inclusion of private equity would not, by itself, constitute a violation of ERISA’s fiduciary duties, provided the fiduciary followed an appropriate process in selecting and monitoring the investment.
On December 21, 2021, during the Biden administration, the DOL issued a Supplemental Statement expressing substantial reservations about the use of private equity investments in defined contribution plans. The statement cautioned that fiduciaries of typical individual account plans were unlikely to possess the expertise necessary to evaluate private equity investments, thereby discouraging their inclusion in 401(k) investment options.
The August 2025 Executive Order
The executive order directs the DOL to reexamine its prior guidance concerning alternative assets and consider regulatory or other guidance clarifying the fiduciary process for offering professionally managed asset allocation funds that include such investments.
The order also calls for consideration of regulatory safe harbors intended to reduce the threat of litigation against fiduciaries who prudently select and monitor these investments. In particular, it seeks to address the potential chilling effect of litigation alleging excessive fees, investment underperformance, or imprudent selection of complex assets.
The DOL was directed, within 180 days, to review its existing guidance and consider whether additional regulations or guidance would be appropriate. The order also directs the Securities and Exchange Commission (SEC) to examine potential changes within its jurisdiction that could facilitate broader access to alternative investments.
The executive order defines “alternative assets” broadly to include:
- Private market investments, including private equity, private credit, and other nonpublicly traded financial instruments.
- Direct and indirect real estate investments, including real estate debt.
- Actively managed investment vehicles that invest in digital assets, including cryptocurrencies.
- Direct and indirect investments in commodities.
- Infrastructure financing investments.
- Lifetime income investment strategies, including longevity risk-sharing pools.
The executive order thus signals a significant policy shift toward expanding access to alternative investments in defined contribution plans by reducing perceived regulatory and litigation barriers.
Fiduciary Considerations for 401(k) Plan Sponsors
Notwithstanding the administration’s policy objectives, the inclusion of alternative investments in 401(k) plans continues to raise significant fiduciary considerations.
1. ERISA’s fiduciary standards remain applicable. The duties of prudence, loyalty, and diversification under ERISA § 404 have not changed. Plan fiduciaries must act solely in the interests of participants and beneficiaries and exercise appropriate care, skill, prudence, and diligence in selecting and monitoring investment alternatives. An executive order does not itself provide an exemption from these obligations.
2. Regulatory guidance may change with future administrations. DOL guidance issued under the Trump administration could be challenged in court, modified, or reversed by a subsequent administration. Fiduciaries should not rely solely on an administration’s favorable policy toward alternative investments.
3. Alternative investments may increase fiduciary litigation exposure. Plan fiduciaries face potential claims arising from investment losses, underperformance, excessive fees, or inadequate evaluation of complex and illiquid investment vehicles. Regulatory encouragement of these investments does not eliminate the possibility of private litigation under ERISA.
4. A thorough and well-documented fiduciary process is essential. Fiduciaries should carefully evaluate proposed alternative investments, including their expected risk-adjusted returns, fees, liquidity restrictions, valuation methodologies, diversification characteristics, and the qualifications of investment managers. The selection and monitoring process should be documented.
5. Investment policies and monitoring procedures should be reviewed. Plan sponsors considering alternative investments should review their investment policy statements, strengthen due diligence procedures, assess the need for specialized investment expertise, and establish appropriate monitoring standards. Participant communications and education may also require attention.
6. Meaningful litigation reform may require congressional action. Although DOL regulations or safe harbors may help fiduciaries demonstrate compliance with ERISA’s prudence requirements, administrative action cannot eliminate ERISA’s statutory private right of action. Broader limitations on fiduciary litigation may require legislation.
7. The characteristics of alternative assets present special risks. Private equity, private credit, real estate, and similar investments may involve substantial illiquidity, comparatively high fees, valuation difficulties, limited transparency, and uncertain performance. Fiduciaries must weigh any potential diversification or return benefits against these risks and costs.
8. Participant-directed 401(k) plans pose particular challenges. Traditional 401(k) plans generally depend upon participants making their own investment decisions, often with limited investment knowledge. Alternative assets may require specialized expertise and long investment horizons. Their inclusion within professionally managed, diversified asset allocation funds may therefore be more suitable than offering such investments as stand-alone options for participant selection.
Conclusion
The August 7, 2025 executive order represents an important change in federal policy toward alternative investments in 401(k) plans. It seeks to make investment opportunities traditionally available to institutional investors more accessible to participants in defined contribution plans.
Nevertheless, greater regulatory acceptance does not necessarily make these investments appropriate for every plan. Fiduciaries must continue to evaluate investment costs, liquidity, valuation, diversification, and participant characteristics under ERISA’s established fiduciary standards.
The critical question remains not whether alternative assets are permitted in a 401(k) plan, but whether their inclusion is prudent for the particular plan and its participants.